Should I Pay Off My Student Loans or Invest in a TVC?
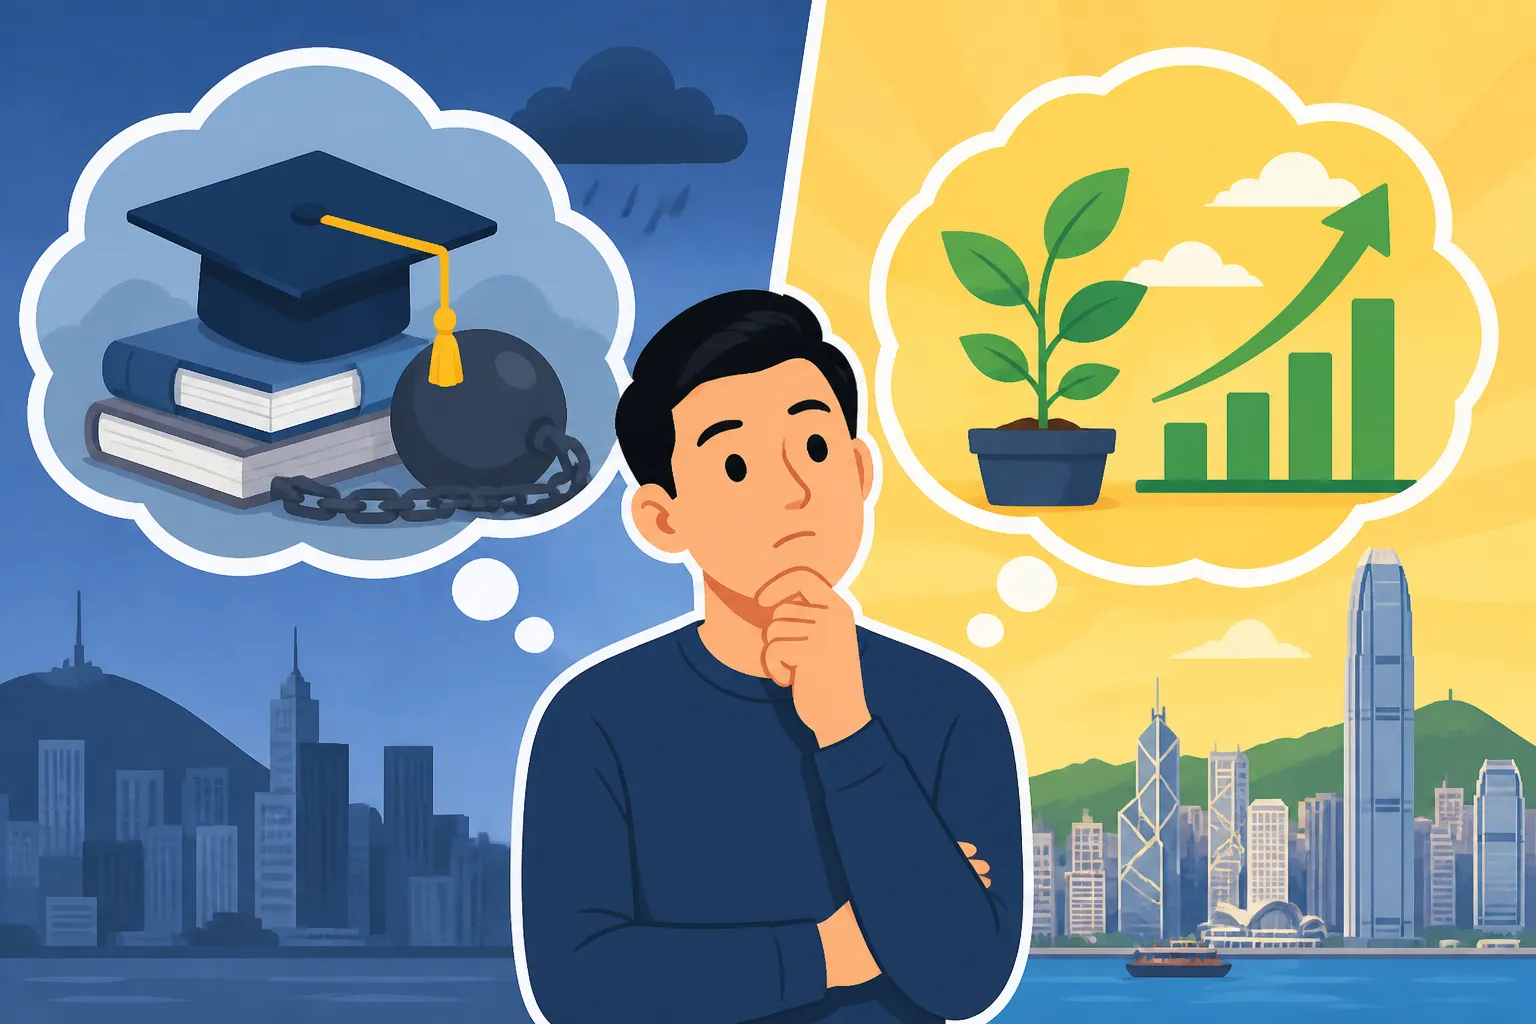
Moving to Hong Kong is a financial whirlwind, isn't it? You’re navigating a new currency, often higher expenses, and suddenly, those student loans from back home feel like an anchor. At the same time, you're hearing about ways to optimize your finances here, like Tax Deductible Voluntary Contributions (TVCs), and you’re left wondering: should I dump all my spare cash into paying off that old debt, or should I be smart and invest in my future here in Hong Kong? This guide will dive deep into this common expat dilemma, helping you weigh the pros and cons to figure out the best path for your unique situation.
Understanding Your Financial Landscape in Hong Kong
When you land in Hong Kong, your financial world expands, but so do the complexities. You've got your global obligations, like those student loans, and then you've got the local opportunities and rules, especially around things like tax and retirement savings. It's a balancing act, and honestly, it can feel a bit overwhelming trying to figure out what takes priority.
The Weight of Student Loans for Expats
Let's be real, those student loans don't just magically disappear when you cross borders. They're often a significant chunk of debt many expats carry. You might have government-backed loans from your home country, which sometimes offer more flexible repayment plans, or you could be dealing with private loans that come with stricter terms and often higher, less forgiving interest rates. Then there are the international student loans, which might have their own set of rules entirely.
The interest rates on these loans are a critical factor. A 3% interest rate might feel manageable, but if you're looking at something closer to 7% or even 10% on a private loan, that debt is growing substantially over time. Imagine that money literally draining from your bank account each month, going straight to interest rather than reducing the principal. It’s a bitter pill to swallow. Adding to this, as an expat in Hong Kong, you’re likely earning in Hong Kong Dollars (HKD), but your student loan repayments are probably in your home currency. This exposes you to currency exchange rate fluctuations. A strong HKD can make repayments feel lighter, but if the HKD weakens against your home currency, your monthly payment in HKD terms could suddenly spike, eating into your budget more than you anticipated. This unforeseen volatility can be a major source of stress and uncertainty, making financial planning a moving target.
The Appeal of Tax Deductible Voluntary Contributions (TVCs)
On the flip side, Hong Kong offers some appealing financial incentives, especially when it comes to saving for retirement. One such avenue is the Tax Deductible Voluntary Contributions (TVCs). These are basically additional contributions you can make to your Mandatory Provident Fund (MPF) scheme, or even to an approved TVC scheme offered by MPF providers, specifically designed to help you save more for retirement while enjoying some lovely tax benefits. Think of it as a way to boost your long-term savings while simultaneously lowering your current year's tax bill.
The core appeal of TVCs lies in their tax-deductible nature. The Hong Kong government allows you to deduct eligible TVC contributions from your assessable income for salaries tax purposes, up to a certain maximum limit. This means that if you contribute to a TVC, a portion of that money effectively reduces the income on which you pay tax, potentially moving you into a lower tax bracket or simply reducing your overall tax liability. It’s a win-win: you’re saving for your future, and the taxman isn’t taking as much from your present earnings. While your existing MPF contributions are mandatory, TVCs give you an extra layer of control and a direct financial incentive to plan proactively for your post-work years. To understand more about the standard contributions and options, check out our guide on Mandatory Provident Fund (MPF): Contribution Rules and Options.
A Head-to-Head Comparison: Loans vs. TVCs
So, here's the core question: which one should you prioritize? The answer isn't a simple one-size-fits-all, as it hinges heavily on your individual circumstances, risk appetite, and financial goals. But we can break down the arguments for each.
Prioritizing High-Interest Debt Repayment
For many financial experts, and frankly, for many expats who just want that monkey off their back, the immediate repayment of high-interest debt is often the recommended first step. Why? Because paying off a loan with a high interest rate is essentially a "guaranteed return" on your money. If your student loan has an interest rate of, say, 7%, every dollar you put towards paying it off saves you 7% in interest that you would have otherwise paid. This is a risk-free return, something that's incredibly hard to match in the investment world, especially in today's volatile markets.
Consider a scenario where you have a private student loan with an 8% interest rate. If you have HKD 10,000 extra cash, putting it into a TVC might save you, let's say, 17% in tax (if you're in a high tax bracket), which is HKD 1,700 for the year. But that 8% loan is costing you HKD 800 per year on that HKD 10,000 principal. Over several years, the interest savings from paying down the loan could easily outpace the tax benefit, especially once you factor in compounding interest on the debt. It provides a clear, tangible reduction in your ongoing financial obligations. The sense of relief from being debt-free, especially from high-interest loans, is also a significant psychological boost, freeing up mental space and future cash flow for other opportunities.
Maximizing Tax Savings with TVCs
However, there are compelling arguments for prioritizing TVCs, especially if your student loan interest rates are relatively low, or if you find yourself in a higher Hong Kong tax bracket. The tax deduction offered by TVCs can be quite powerful. Currently, you can claim a deduction for TVC contributions and Qualifying Deferred Annuity Policies (QDAP) up to a combined maximum of HKD 60,000 per year. For a deep dive into this, refer to our guide on Claiming the HKD 60,000 Tax Deduction for TVC and QDAP.
Let's imagine your highest marginal tax rate in Hong Kong is 15%. Contributing HKD 60,000 to a TVC could reduce your tax bill by a cool HKD 9,000. If your student loan has an interest rate of only 3% or 4%, that HKD 9,000 tax saving is a much higher "return" in the short term than the interest you'd save by paying down a similar amount of debt. Furthermore, the money in your TVC account is invested, typically in a range of funds, giving it the potential for long-term growth, even if that growth isn't guaranteed. This approach essentially uses the government's tax incentive to kickstart or boost your retirement nest egg while potentially paying off your student loan at its regular, lower-interest pace. For more details on the tax system, you might want to read our comprehensive Hong Kong Tax Guide for Expats: Salaries Tax and Filing (2026).
The Psychological Aspect and Financial Freedom
Beyond the pure numbers, there's a significant psychological component to this decision. Carrying debt, especially student loan debt that feels like a vestige of a past life, can be incredibly draining. The constant reminder of monthly payments, the worry about interest accruing, and the feeling of not being truly financially "free" can impact your overall well-being. For some, the sheer relief of eliminating that debt is worth more than any potential tax savings or investment gains. It liberates cash flow and allows for a fresh start with your financial planning in Hong Kong.
On the other hand, actively contributing to your retirement fund through TVCs can give a strong sense of purpose and security. Knowing you're building a substantial nest egg for your future, leveraging tax benefits along the way, can be incredibly motivating. It's about setting yourself up for long-term stability in Hong Kong, which, let's be honest, often means putting down roots, even if temporary. This sense of building something for yourself can offset the immediate gratification of debt repayment, especially if you have a high tolerance for managing outstanding debt.
Crafting Your Personal Strategy: Factors to Consider
There's no magic formula, but by carefully evaluating your specific situation, you can lean towards the strategy that aligns best with your financial reality and comfort level.
Interest Rates and Loan Terms
The first, and arguably most important, factor is the nitty-gritty of your student loans. You need to know your exact interest rates. Do you have multiple loans with varying rates? It's usually wise to tackle the highest-interest ones first, employing what's often called the "debt avalanche" method. A loan with a 7-8% or higher interest rate should almost always take priority over a TVC contribution, purely from a mathematical standpoint, as that's a hefty guaranteed return you're missing out on. Conversely, if your student loans are at a historically low 2-3%, then the tax savings and potential investment growth from a TVC might make it a more attractive option.
Beyond the rate, understand your loan terms. Are there any prepayment penalties? Many student loans don't have them, allowing you to make extra payments without a fee. What are the repayment schedules like? Are they flexible, or do they lock you into rigid monthly payments? Also, consider if your interest rate is fixed or floating. A floating rate introduces an element of uncertainty; if rates are expected to rise globally, paying off that variable-rate loan sooner might be a very smart move to insulate yourself from future payment spikes. When making these international payments, tools like Wise can be incredibly helpful for managing currency conversions and often offer better rates than traditional banks, saving you a bit more on each transfer.
Your Hong Kong Tax Bracket and Income
Hong Kong's tax system is generally considered expat-friendly, with low salaries tax rates. However, your specific tax bracket plays a crucial role in the attractiveness of TVCs. If you're in a higher tax bracket, say paying the standard rate of 15% or the progressive rates that can go up to 17% (after hitting the threshold for the 16% bracket), the tax savings from TVC contributions become more significant. For instance, if you earn enough to be taxed at the highest marginal rates, a HKD 60,000 TVC contribution will yield a higher tax saving than if you're in a lower bracket. This makes the TVC a more potent tool for tax efficiency for higher earners. You can review the specifics of tax rates in our article on Salaries Tax Rates: 15% Standard vs Two-Tiered 16% for High Earners.
It's vital to look at your total assessable income and how TVC contributions might reduce it. If your income is already below certain thresholds, or if you have other substantial deductions, the incremental tax benefit from a TVC might be less impactful. For many expats, understanding their tax situation can be complex, especially with potential overseas income or deductions. Consulting with a specialist like Taxes for Expats can provide tailored advice on how best to leverage tax-saving mechanisms in Hong Kong. They understand the nuances of expat taxation, which is a game-changer when you're trying to optimize your financial strategy.
Future Financial Goals and Risk Tolerance
Your long-term plans in Hong Kong also heavily influence this decision. Do you see yourself staying in Hong Kong for the long haul, perhaps working towards Right of Abode (Permanent Residency): The 7-Year Journey? If so, building a robust retirement fund through MPF and TVCs makes a lot of sense. The longer your money is invested, the more time it has to grow through compounding. If you plan to leave Hong Kong in a few years, the immediate tax benefit of TVCs is still there, but the long-term investment growth might be less relevant, and you might prefer the liquidity of having your debt paid off. Remember, MPF and TVC funds are generally locked until retirement age (65), or specific conditions like permanent departure from Hong Kong are met, as detailed in Withdrawing MPF: Early Withdrawal vs Permanent Departure from HK.
Your risk tolerance also comes into play. Paying off debt is a risk-free return; you know exactly what you're saving. Investing in TVCs, while tax-efficient, means your money is in investment funds, subject to market fluctuations. If you're highly risk-averse, the certainty of eliminating debt might bring you more peace of mind than the potential, but not guaranteed, growth of a TVC. Think about your overall financial picture, including your emergency fund, other investments, and your general comfort with debt versus market exposure.
Here's a quick overview to help you visualize the trade-offs:
| Feature | Paying Off Student Loans | Investing in TVCs (Tax Deductible Voluntary Contributions) |
|---|---|---|
| Financial Outcome | Guaranteed return (interest saved); Debt elimination | Potential for investment growth; Tax savings |
| Risk Profile | Low (risk-free return) | Medium (market fluctuations apply) |
| Liquidity | Increases immediate cash flow post-repayment | Funds generally locked until retirement/permanent departure |
| Psychological Impact | Freedom from debt burden, clarity | Building long-term wealth, sense of future security |
| Tax Benefit | Indirect (more disposable income post-tax) | Direct (deductible from assessable income, up to HKD 60,000) |
| Best For | High-interest loans, risk-averse individuals, short-term HK plans | Lower-interest loans, higher tax brackets, long-term HK plans |
Making an Informed Decision
Ultimately, this is a personal financial decision, and what works for one expat might not work for another. It's about finding the balance that makes sense for your life and your unique situation.
Consulting Financial Professionals
If you’re genuinely torn, or if your financial situation is particularly complex, don't hesitate to seek personalized advice from a qualified financial professional in Hong Kong. They can analyze your specific loan terms, your current income and tax situation, and your long-term goals to provide a tailored recommendation. Many independent financial advisors here specialize in helping expats navigate these exact dilemmas, taking into account both your home country's financial context and Hong Kong's opportunities. They can help you understand all the nuances, from your Salaries Tax Rates: 15% Standard vs Two-Tiered 16% for High Earners to the intricacies of your specific MPF plan and how TVCs integrate.
They might also point out other financial planning areas, such as optimizing your overall Everyday Budgeting in HK: Cost of Living Benchmarks (2026) or exploring other investment vehicles. Remember, while a blog post can offer general guidance, a professional can offer advice tailored to your exact circumstances.
The Hybrid Approach
Sometimes, the best solution isn't an either/or, but a bit of both. A "hybrid approach" can often be the most sensible and balanced strategy. This might involve:
- Aggressively tackling your highest-interest student loan first. Dedicate a significant portion of your spare income to eliminating this debt, as it provides the greatest guaranteed return.
- Simultaneously making some TVC contributions, especially up to the HKD 60,000 deduction limit, if you're in a higher tax bracket. Even if it's not the full amount, contributing enough to capture a meaningful tax saving is a smart move. This ensures you're still leveraging Hong Kong's tax incentives while chipping away at your debt.
- Once the high-interest debt is gone, then re-evaluate. With that burden lifted, you can then redirect even more funds towards TVCs or other investments, accelerating your retirement savings.
For example, if you have HKD 10,000 extra per month, you might put HKD 7,000 towards a 7% student loan and HKD 3,000 towards your TVC. This way, you're making progress on both fronts. As your loan balance decreases, more of your payments go towards principal, speeding up the repayment process. Once it’s fully paid, you can then funnel that entire HKD 10,000 into your TVC, or perhaps explore other investment avenues like those discussed in Wealth Management in HK: Offshore Accounts and Brokerages. The key is to be intentional and adjust your strategy as your financial situation and priorities evolve. Don't forget, managing your remittances efficiently when paying off international loans is crucial; services like Wise can help you save money on exchange rates and fees.
Navigating your finances as an expat in Hong Kong is a continuous journey. Whether you prioritize debt repayment or retirement savings through TVCs, the most important thing is to make a conscious, informed decision that brings you closer to your personal financial goals.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute financial, tax, or legal advice. While we strive to provide accurate and up-to-date content, the financial landscape in Hong Kong and global regulations can change rapidly. Readers should consult with qualified financial advisors, tax professionals, or legal experts for advice tailored to their specific circumstances. We do not endorse any specific financial products, services, or companies mentioned herein.