Understanding the Fixed Exchange Rate: HKD Peg to USD
One of the first things that throws many expats arriving in Hong Kong for the first time is the currency. You hear "Hong Kong Dollar," but then everyone talks about it in relation to the US Dollar, and it's all a bit confusing. You're trying to set up your bank accounts, understand your salary, and figure out how much things really cost, and this whole "peg" business just adds another layer of complexity. Trust me, I've been there, scratching my head at the ATM. This guide is here to unravel the mystery of the Hong Kong Dollar's fixed exchange rate to the US Dollar, explaining what it means for your finances and daily life here in this dynamic city.
What Exactly is the HKD-USD Peg? The Basics for Expats
When you first hear about the Hong Kong Dollar (HKD) being "pegged" to the US Dollar (USD), it can sound a bit arcane, almost like financial wizardry. But at its heart, it's a very deliberate and robust system designed to maintain economic stability. For expats, it's one of those foundational pieces of knowledge that impacts everything from your salary's real value to how you think about sending money home or making international investments. It’s not just a technicality; it’s a pillar of Hong Kong's financial landscape.
A Brief History: Why Hong Kong Chose the Peg
To truly grasp the significance of the HKD-USD peg, we need a quick trip back in time to the early 1980s. Hong Kong was facing a period of immense uncertainty, not just economically, but politically. The negotiations over the city's future, as it transitioned from British rule back to China, created significant jitters in the financial markets. The Hong Kong Dollar, which at that time had a floating exchange rate, experienced extreme volatility, causing widespread panic and a crisis of confidence. Imagine waking up each day to find your savings rapidly losing value against major international currencies – it was a scary time, indeed.
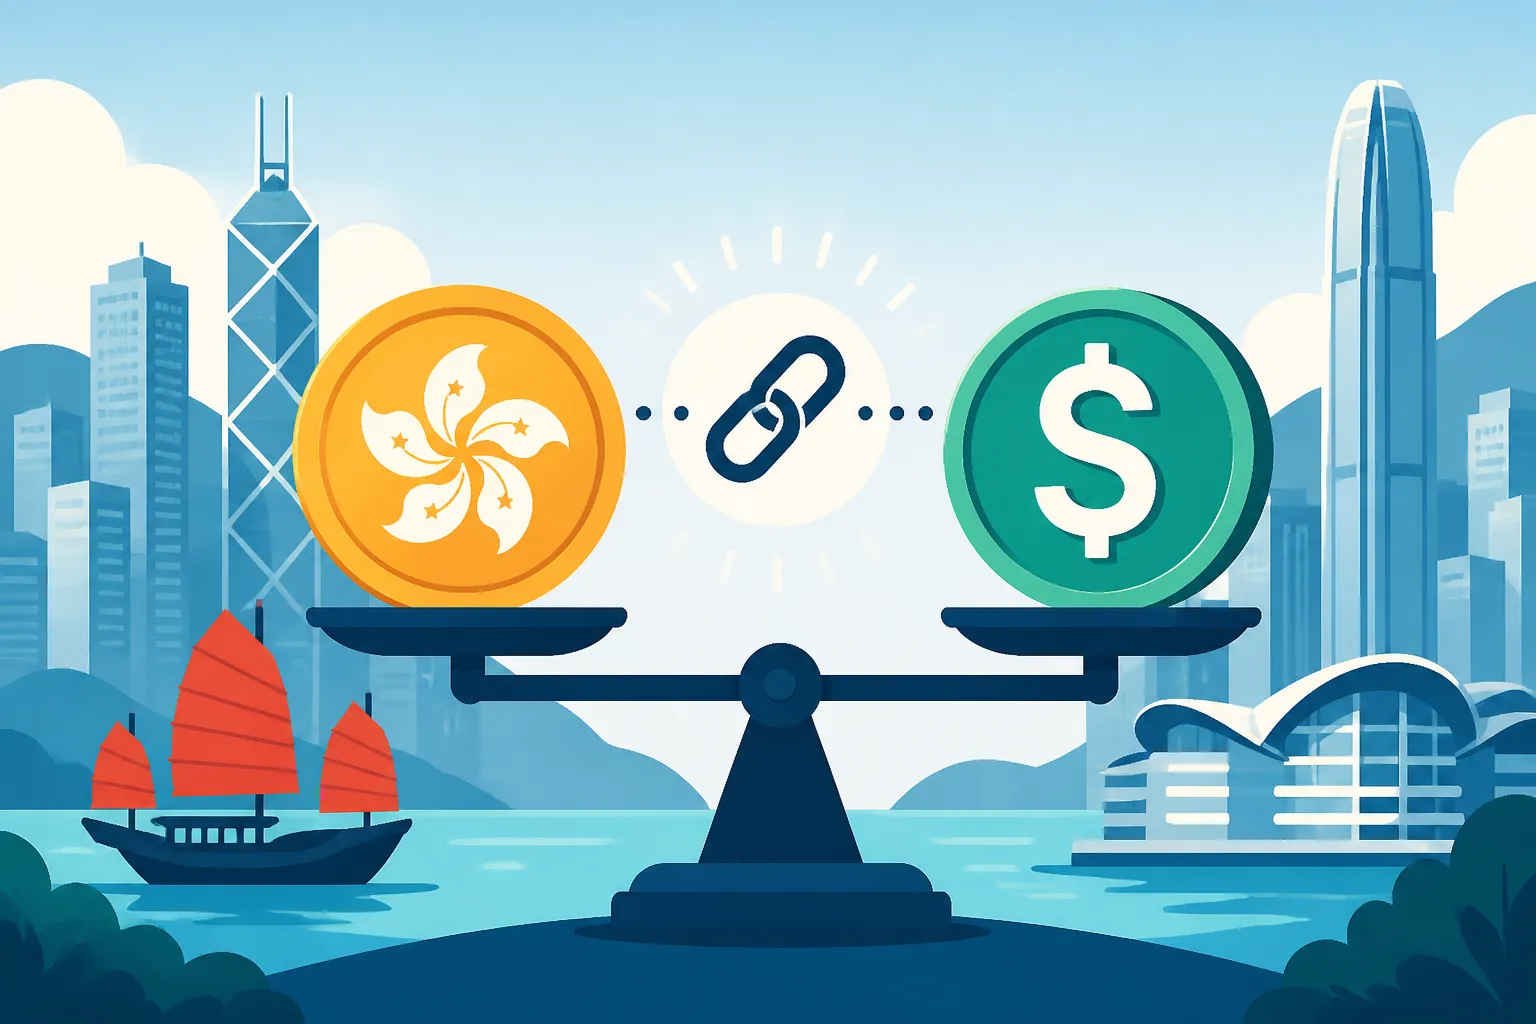
In response to this looming crisis, the Hong Kong government, specifically the Hong Kong Monetary Authority (HKMA), made a pivotal decision in October 1983. They introduced the Linked Exchange Rate System (LERS). The primary goal was clear: restore confidence in the HKD by eliminating exchange rate risk against the world's most dominant currency, the US Dollar. By pegging the HKD to the USD, Hong Kong aimed to provide a stable financial environment, attract foreign investment, and reassure both local residents and international businesses that their money's value would not erode due to currency fluctuations. It was a bold move, one that has largely served Hong Kong well for over four decades, providing a predictable financial anchor in a sea of global economic changes.
The Mechanics of the Linked Exchange Rate System (LERS)
So, how does this "peg" actually work in practice? It's more sophisticated than just setting a single fixed number. The Linked Exchange Rate System (LERS) operates on a "currency board" arrangement. What that means is the HKMA commits to exchange HKD for USD, and vice-versa, at a fixed rate within a very narrow band.
Specifically, the HKD is pegged to the USD at a central rate of HK$7.80 to US$1. But it's not a rigid, unmoving line. Instead, the HKMA maintains a "convertibility zone" or "bands." They intervene in the market if the HKD deviates too much from this central rate. The HKMA is obliged to buy US dollars from licensed banks when the HKD strengthens to 7.75 per USD, and to sell US dollars when the HKD weakens to 7.85 per USD. These are known as the strong-side and weak-side Convertibility Undertakings, respectively.
Here's the crucial part: the system is backed by Hong Kong's enormous foreign exchange reserves, which are more than three times the monetary base. This huge war chest gives the HKMA the firepower to defend the peg by buying or selling HKD as needed. When the HKD hits 7.75, the HKMA buys USD from banks, injecting HKD into the market and putting downward pressure on the HKD's value until it falls back within the band. Conversely, if the HKD hits 7.85, the HKMA sells USD to banks, withdrawing HKD from circulation and putting upward pressure on its value. This mechanism ensures that the HKD always trades within this narrow range against the USD, providing a remarkable degree of stability that few other currencies enjoy.
| Aspect | Description |
|---|---|
| Central Peg Rate | HK$7.80 = US$1.00 |
| Strong-side Convertibility | HKMA buys USD from licensed banks at HK$7.75 = US$1.00 (injects HKD into market) |
| Weak-side Convertibility | HKMA sells USD to licensed banks at HK$7.85 = US$1.00 (withdraws HKD from market) |
| Intervention Mechanism | Automatic market operations by HKMA when exchange rates hit the strong or weak limits of the band. |
| Backing | Fully backed by Hong Kong's substantial foreign exchange reserves, far exceeding the monetary base. |
| Primary Goal | Maintain monetary and financial stability, eliminate exchange rate risk, and foster confidence. |
This means that for you, as an expat in Hong Kong, the value of your HKD earnings relative to the USD is remarkably predictable. You won't see wild swings day-to-day like you might with other major currency pairs. This predictability is a huge advantage, especially when you're managing cross-border finances or making plans that involve overseas payments.
How the Peg Affects Your Everyday Expat Life and Finances
Living in Hong Kong, you’ll quickly realise that the HKD-USD peg isn't just some abstract economic concept; it's interwoven into the very fabric of your financial reality here. From your monthly salary to your rent payments, and especially when you're thinking about sending money back home, the stability offered by the peg plays a significant, often unacknowledged, role. It’s one of those things that, once you understand it, makes navigating your expat finances a whole lot clearer.
Stability Amidst Global Turbulence: A Double-Edged Sword
The most immediate and noticeable impact of the HKD-USD peg is the incredible stability it offers. In a world increasingly prone to economic shocks and currency volatility, Hong Kong's currency remains a steadfast anchor. When global markets are in turmoil, or other currencies are experiencing sharp depreciations or appreciations, the HKD stays firmly within its narrow band against the USD. This is fantastic for business confidence and helps Hong Kong maintain its status as a leading international financial centre. For an expat, this translates to a sense of security. You know that the value of your salary, once converted to HKD, isn't going to suddenly halve overnight against the US dollar due to some unforeseen market event. This stability simplifies financial planning immensely.
However, it's also a double-edged sword. While the peg protects against downside volatility, it also means that the HKD cannot appreciate independently against the USD. If the US dollar weakens significantly against other major global currencies (like the Euro, Yen, or Pound), the HKD will, by extension, also weaken against those currencies, even if Hong Kong's own economy is booming. This means that if your home currency isn't USD, or if you frequently make payments in other non-USD currencies, the peg might not always feel like an advantage. You might find that the cost of imported goods from Europe, or a holiday trip to Japan, fluctuates based on the USD's global strength, not directly Hong Kong's economic performance. It’s a trade-off: stability against the USD at the cost of independent movement against other global currencies.
Impact on Salaries, Rent, and Cost of Living
For many expats, your salary in Hong Kong will be denominated in HKD. Thanks to the peg, if your employment contract specifies a certain HKD amount, you can rest assured that its USD equivalent will remain largely consistent. This is particularly beneficial for those who have financial commitments or assets back in the US, or who plan to eventually repatriate their earnings to USD. The predictability allows for clearer budgeting and investment strategies in USD terms.
When it comes to rent, often one of the largest expenses in Hong Kong, the peg's influence is also felt. Many landlords or property agencies will quote prices in HKD, and again, the stability against the USD means that the underlying cost in USD terms is predictable. This is true whether you're living in a bustling neighbourhood like Kennedy Town or a more spacious area like Discovery Bay. This also applies to the broader cost of living in Hong Kong. While local inflation and supply/demand dynamics play a huge role in the prices of goods and services, the stability of the currency against the USD means that the cost of imported goods (many of which are priced or influenced by USD rates globally) remains relatively stable in HKD terms. This is a subtle but significant factor in how Hong Kong maintains its status as an expensive, but often predictable, place to live.
Implications for International Transfers and Investments
This is where the HKD-USD peg truly shines for many expats, especially those managing money across borders. If you're a US citizen or someone whose primary financial hub is in USD, the process of sending money home or bringing money into Hong Kong is greatly simplified. You essentially eliminate one layer of currency risk. When you transfer funds from a USD account to a HKD account, or vice-versa, the exchange rate will consistently fall within the 7.75-7.85 band, making the transaction predictable. This is a huge boon for planning remittances or managing your portfolio. Services like Wise and traditional banks offer competitive rates for these transfers, with the underlying peg removing much of the exchange rate guesswork. You can learn more about different ways of Sending Money Home: International Remittances and Forex Rates.
However, if your home currency is, say, the British Pound or the Euro, the situation is slightly different. When you convert HKD to GBP, you're effectively performing two conversions: HKD to USD (fixed) and then USD to GBP (floating). This means the fluctuating part of the equation lies in the USD-GBP rate. This is still generally a more straightforward scenario than dealing with a completely free-floating HKD against GBP, as it isolates the volatility to one major currency pair. For expats thinking about long-term investments, especially those denominated in foreign currencies, understanding this dual conversion is key. You'll need to monitor the USD's performance against your target investment currency, rather than worrying about the HKD's independent movement. Platforms and financial advisors often recommend strategies that account for this structure, ensuring your wealth management aligns with the peg's realities. For a comprehensive overview of your financial obligations, consider checking out the Hong Kong Tax Guide for Expats: Salaries Tax and Filing (2026).
Dispelling Common Myths and Anxieties About the HKD Peg
Despite its long-standing success and stability, the HKD-USD peg occasionally sparks debates and anxieties, especially among those new to Hong Kong's financial landscape. You'll hear chatter, see speculative articles, and sometimes even get worried questions from friends and family overseas about the "sustainability" of the peg. These concerns are often rooted in a misunderstanding of how the system fundamentally works and the sheer commitment the Hong Kong Monetary Authority has to maintaining it. Let’s tackle some of these common myths head-on.
Is the Peg Sustainable? Addressing De-pegging Fears
One of the most persistent questions you'll hear is whether the HKD-USD peg is truly sustainable, particularly during times of economic stress or geopolitical tension. Fears of "de-pegging" – that is, Hong Kong abandoning the fixed exchange rate system – periodically surface. These fears often stem from historical instances where other countries have struggled to maintain their currency pegs, leading to economic instability. However, Hong Kong's situation is uniquely strong.
Firstly, the HKMA has an unprecedented level of foreign exchange reserves. Hong Kong’s official foreign exchange reserves are massive, often exceeding several times the city's monetary base. This immense financial firepower provides a robust buffer, allowing the HKMA to intervene confidently in the market to defend the peg at any time. Unlike countries that might struggle with dwindling reserves when facing speculative attacks, Hong Kong is exceptionally well-resourced. This means they have ample US dollars to sell when the HKD is weak and needs support, and sufficient HKD to inject when the currency is strong.
Secondly, the commitment to the peg is not just financial; it's deeply ingrained in Hong Kong's economic policy and credibility. The LERS is seen as a cornerstone of Hong Kong's stability and its appeal as an international financial hub. Abandoning it would severely damage investor confidence and economic predictability, something the HKMA and the government are acutely aware of and committed to avoiding. Any discussion of de-pegging is often speculative and overlooks the fundamental strength and strategic importance of the system to Hong Kong's identity.
How the HKMA Defends the Peg: The Intervention Zone
Understanding the HKMA's active role in defending the peg can further alleviate concerns about its sustainability. It's not a passive system; it's actively managed through precise intervention mechanisms. As we discussed, the HKMA has set strong-side (HK$7.75) and weak-side (HK$7.85) convertibility undertakings. These aren't just theoretical limits; they are active intervention points.
When the market pushes the HKD to the edge of this "intervention zone," the HKMA steps in. If the HKD strengthens to 7.75 against the USD, the HKMA buys USD from the banks, effectively increasing the supply of HKD in the market. This increased supply then naturally puts downward pressure on the HKD's value, bringing it back within the desired band. Conversely, if the HKD weakens to 7.85, the HKMA sells USD to banks, withdrawing HKD from circulation. This reduction in HKD supply then strengthens its value, pulling it back towards the 7.80 central rate.
This system is automatic and transparent. Market participants know exactly what the HKMA will do, which actually discourages speculative attacks because the outcome is predictable and the HKMA has unlimited capacity (given its reserves) to defend the band. The convertibility undertakings are firm commitments, not discretionary policies. This predictable intervention mechanism is a critical factor in why the peg has endured so successfully through various regional and global financial crises, providing a robust and reliable framework for Hong Kong's economy and, by extension, your personal finances as an expat.
Practical Tips for Managing Your Finances with the Peg in Mind
Navigating your finances in Hong Kong doesn't have to be daunting, especially once you get a handle on the HKD-USD peg. It actually offers a unique advantage – predictability – which you can leverage for smarter money management. Whether it's timing your currency exchanges or choosing the right platforms for international transfers, understanding the peg's dynamics can genuinely save you money and headaches. And for those looking to optimize their tax situation, remember resources like Taxes for Expats can provide tailored advice for your unique cross-border circumstances.
When to Exchange Currency: Taking Advantage of the Band
While the HKD is pegged, it does fluctuate slightly within its 7.75-7.85 band. For everyday transactions, these small movements won't make a huge difference, but for larger sums—like a significant portion of your salary, a down payment, or repatriating savings—even a few pips can add up.
The general advice is this:
- If you're converting USD to HKD: You want to get more HKD for your USD. This happens when the HKD is closer to the strong end of the band (i.e., closer to HK$7.75 per USD). This means USD is relatively "cheaper" against HKD, and your US dollars buy more Hong Kong dollars.
- If you're converting HKD to USD: You want to pay less HKD for your USD. This happens when the HKD is closer to the weak end of the band (i.e., closer to HK$7.85 per USD). Here, HKD is relatively "cheaper" against USD, so it takes fewer Hong Kong dollars to buy one US dollar.
Keep an eye on the real-time HKD/USD exchange rate. Most banking apps or financial news sites will display this. While the movements are small, they are consistent. For instance, if you're planning a large transfer, waiting for the rate to move by even a few pips in your favour (e.g., from 7.80 to 7.82 when converting HKD to USD) could result in tangible savings. This proactive approach to exchange can be a smart part of your overall Everyday Budgeting in HK: Cost of Living Benchmarks (2026).
Choosing the Right Platforms for International Remittances
For many expats, regularly sending money home is a fact of life. Given the HKD's peg to the USD, this process is generally quite efficient, especially if your home currency is USD. However, even with the peg, the fees and exchange rate markups applied by different service providers can vary significantly.
Traditional banks, while reliable, sometimes have higher transfer fees or less favourable exchange rates within the convertibility zone. This is where dedicated money transfer services, like Wise, really come into their own. They often offer more transparent fee structures and exchange rates very close to the mid-market rate, which can lead to considerable savings over time. For example, if you're sending HKD to a USD account, Wise will typically give you a rate very close to the current spot rate within the 7.75-7.85 band, with a clear breakdown of their (usually low) fee.
When choosing a platform, consider:
- Exchange Rate Transparency: Is the rate you see the rate you get, or are there hidden markups?
- Fees: Are they fixed, percentage-based, or both? How do they compare to other services?
- Speed: How quickly do the funds arrive?
- Limits: Are there minimum or maximum transfer amounts?
Don't just stick with your first bank's offering without checking. A little research into platforms like Wise could result in significant savings on your regular remittances. For those Receiving Foreign Currency Salary into a HK Bank Account, understanding these nuances is equally important. And if you're delving into your annual tax obligations, understanding your income and transfers will be crucial when you're Filing BIR60 via eTAX: Step-by-Step Guide for Expats.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.