Consolidating Multiple MPF Accounts via the eMPF Platform
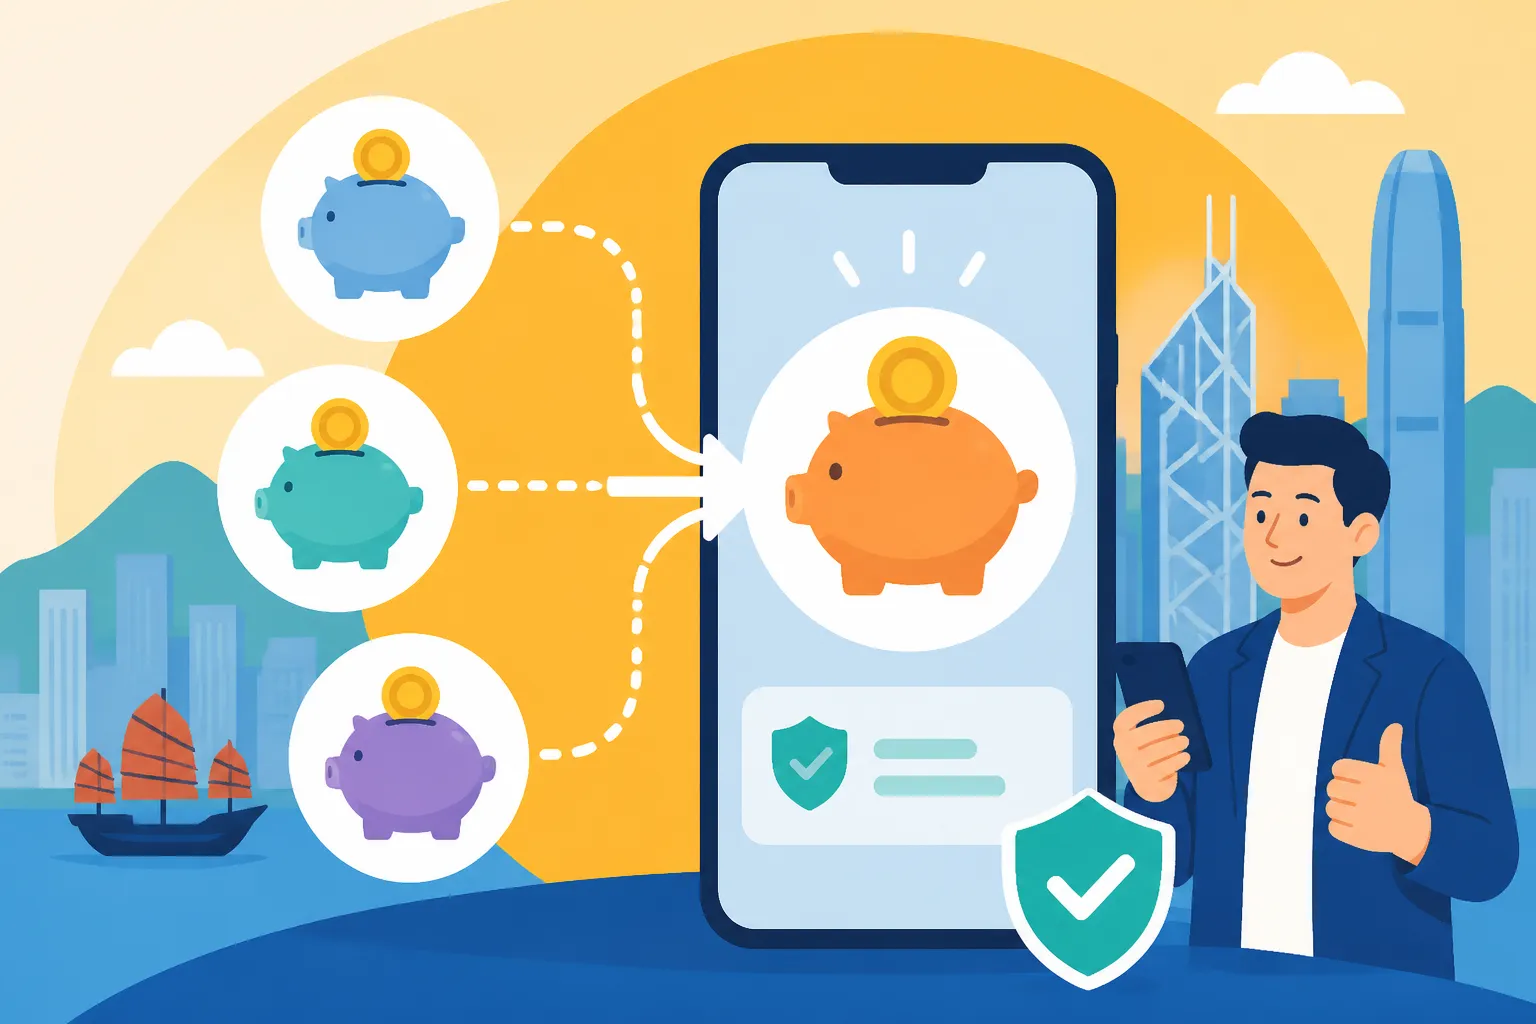
Managing a scattered trail of Mandatory Provident Fund accounts is a headache every long-term expat in Hong Kong eventually faces. I remember the sheer dread of opening my mailbox in Mid-Levels only to find five different statements from five different trustees, each eating away at my savings with administrative fees. This guide simplifies that chaos by showing you exactly how to consolidate your accounts using the eMPF platform.
The Fragmented Reality of Hong Kong Retirement Savings
If you have been in Hong Kong for more than a few years, you likely have a "financial footprint" that is wider than it needs to be. Every time you switch jobs—perhaps moving from a boutique firm in Sheung Wan to a multinational in ICC—your previous employer’s MPF scheme doesn't just disappear. It turns into a "preserved account." If you don't actively move that money, it stays with the original trustee. After three or four career moves, you are suddenly tracking your net worth across multiple logins, different fund performances, and varying fee structures.
The problem with this fragmentation isn't just the mental load; it is the mathematical erosion of your wealth. Each of those separate accounts carries its own set of management fees. While a 1.5% fee might not sound like much, paying it across four different platforms on smaller balances can significantly stunt your long-term compound interest. Furthermore, trying to rebalance your portfolio becomes a nightmare. If you want to move from 100% HK equities to a more conservative global bond mix, you have to log into four different systems to make it happen. This is exactly why understanding Mandatory Provident Fund (MPF): Contribution Rules and Options is the first step toward financial literacy in this city.
Validation of this frustration is important: the old system was designed for trustees, not for users. It relied on paper forms, wet signatures, and weeks of "out-of-market" transit time where your money sat in limbo. Paper forms are sometimes rejected over a signature mismatch, which can delay a transaction by a week or more. The eMPF platform, which became the city's centralized digital backbone in recent years, was built specifically to kill this bureaucracy.
What Exactly is the eMPF Platform
By mid-2026, the eMPF platform has matured into the definitive one-stop shop for all things retirement in Hong Kong. It is a non-profit platform mandated by the government to standardize the administrative side of the MPF system. Before this, every trustee—whether it was AIA, Manulife, or Sun Life—had their own proprietary interface. Some were decent, but many looked like they hadn't been updated since 2005. The eMPF platform acts as a universal front-end, meaning you no longer need to deal with the individual websites of the trustees for basic administrative tasks.
The most significant benefit of the eMPF era is the massive reduction in administration fees. Because the platform centralizes the data and processing, the "administrative" portion of your fund's Expense Ratio (FER) has dropped. This means more of your money stays invested. When you are looking at your total compensation package, understanding Salaries Tax Rates: 15% Standard vs Two-Tiered 16% for High Earners is vital, but your MPF growth is the "shadow salary" that builds your future.
For expats, the eMPF platform also solves the "lost account" problem. Many of us move apartments frequently, and those physical MPF statements often get sent to old addresses in Discovery Bay or Happy Valley. By registering on the eMPF platform, you link your HKID to every account ever opened in your name. The system performs a "sweep" and locates your dormant accounts, bringing them into a single dashboard. It is a moment of digital clarity that I found incredibly satisfying when I first linked my own accounts.
Getting Registered and Authenticated
The first hurdle is the "onboarding" process. To use the eMPF platform, you need a high level of digital authentication. In Hong Kong, this means the "iAM Smart" app. If you haven't set this up yet, you are missing out on most of the city’s digital services. I recommend visiting one of the self-registration kiosks found in MTR stations or Post Offices to get the "iAM Smart+" version, which allows for legal digital signatures.
Once your iAM Smart profile is ready, you can download the eMPF app or log in via the web portal. The system will ask you to verify your identity and will then begin the process of "discovering" your existing MPF accounts. This can take a few minutes as the system queries the databases of all 13+ trustees in the city. When the list populates, don't be surprised if you see accounts you had completely forgotten about from a six-month contract you did years ago.
For those of us who are US citizens or residents of other high-tax jurisdictions, this digital transparency is also a blessing for reporting. Knowing exactly where your "foreign trust" assets are located makes it much easier when working with services like Taxes for Expats to ensure you are compliant with FATCA and FBAR requirements. Having one consolidated statement is infinitely easier to hand over to a tax professional than a shoebox of papers.
Step by Step Guide to Consolidating Your Accounts
Once you can see all your accounts on the eMPF dashboard, the actual consolidation process is surprisingly intuitive. You no longer need to contact your "losing" trustees. You only need to decide which trustee will be your "winner"—the one account that will swallow all the others.
Selecting Your Master Trustee
Choosing which account to keep requires a bit of research. You shouldn't just pick the one with the most money. Instead, look at the fund performance and, more importantly, the fund choices. Does this trustee offer a low-cost Global Equity fund? Do they have a reliable target-date fund? I personally looked for the trustee with the cleanest interface and the lowest fees for the specific funds I wanted.
If you are planning to maximize your benefits, you might also want to look into Tax Deductible Voluntary Contributions (TVC): Maximize Retirement Savings. Some trustees make it very easy to set up a TVC account alongside your regular MPF, which can give you a significant tax break on your Filing BIR60 via eTAX: Step-by-Step Guide for Expats. Once you’ve picked your master account, you simply select the "Consolidation" option within the eMPF app.
Executing the Transfer
Within the app, you will see a list of your preserved accounts. You check the boxes for the accounts you want to move and select your target account. The eMPF platform then generates a digital transfer request. Because you are already authenticated via iAM Smart, you don't need to print anything or mail a single letter to a trustee in Kwun Tong.
The platform will show you a "Transfer Guide" which estimates the time the move will take. Usually, the process takes about 10 to 15 business days. During this time, your "losing" trustee will sell your units into cash, and the "winning" trustee will use that cash to buy new units in your chosen funds. This leads us to the one risk you must be aware of: "Out-of-Market" risk.
Managing Out-of-Market Risk
The biggest fear people have during consolidation is that the market will skyrocket during those 10 days when their money is in cash. While this is a valid concern, the eMPF platform has significantly shortened this window compared to the old paper-based days. To mitigate this risk, I usually avoid consolidating during periods of extreme market volatility. If the Hang Seng Index is swinging 5% a day, maybe wait for a calmer week.
Once the transfer is complete, you will receive a notification through the eMPF app. You can then log in and see your total balance in one place. It is a good time to review your asset allocation. If you are using a service like Wise to manage your international life, you already know the value of having a "borderless" view of your money. Consolidating your MPF is simply doing the same for your local Hong Kong retirement pot.
| Feature | Old Paper-Based System | eMPF Platform (2026) |
|---|---|---|
| Account Discovery | Manual search / contact each trustee | Automatic via HKID/iAM Smart |
| Transfer Method | Paper forms and wet signatures | Digital via App / Web |
| Processing Time | 3 – 4 weeks | 1 – 2 weeks |
| Admin Fees | High (varying by trustee) | Standardized & Lower |
| Transparency | Scattered statements | Centralized Dashboard |
| Address Updates | Must notify each trustee separately | Single update on platform |
Strategic Benefits for the Global Expat
Consolidating your accounts isn't just about tidiness; it's about preparing for your eventual exit from the city. Most expats do not stay in Hong Kong forever. Whether you are heading back to London, moving to Singapore, or retiring in Portugal, you will eventually need to deal with Withdrawing MPF: Early Withdrawal vs Permanent Departure from HK.
When the time comes to leave, having one single account to close out is significantly faster than trying to prove "permanent departure" to four different trustees. Each trustee has their own slightly different requirements for documentation, and trying to coordinate that from overseas is a recipe for a nervous breakdown. Some people spend months chasing old MPF money because they forgot which email address they used for a secondary account ten years ago.
Furthermore, if you are a US expat, consolidating helps with the complexity of "Passive Foreign Investment Company" (PFIC) reporting. Dealing with Taxes for Expats becomes much smoother when you have a single, consolidated annual statement that clearly shows your gains and losses. It simplifies the Double Taxation Relief: US Citizens Filing Taxes in Hong Kong process immensely, as you have a clear paper trail of your Hong Kong tax-deferred contributions.
Managing Your Portfolio Post-Consolidation
Once your money is in one place, you should actually look at what it’s doing. Many expats fall into the trap of "Default Investment Strategy" (DIS). While DIS is a great low-fee option for those who don't want to think about it, as a savvy professional, you might want more control.
The eMPF platform makes it incredibly easy to switch funds. If you feel the US market is overvalued and want to shift toward Asian equities or perhaps a more stable bond fund, you can do it with a few taps. This level of agility was impossible when your money was split across different platforms with different processing speeds.
For those who are sending money out of Hong Kong regularly, perhaps for a mortgage back home or to fund an overseas brokerage account, you are likely already using Wise to avoid those hidden bank markups. Think of your consolidated MPF as the "Hong Kong Pillar" of your global wealth. Just as you wouldn't keep ten different bank accounts with $1,000 in each, you shouldn't keep your MPF scattered.
Technical Troubleshooting and Common Pitfalls
While the eMPF platform is a massive improvement, it isn't perfect. I have encountered a few "expat-specific" issues that you should be aware of. The most common is a name mismatch. If your HKID has your middle name but your old MPF account from 2012 does not, the system might fail to link the two automatically.
In these cases, you may still need to perform a "manual link" by providing the account number from an old statement. This is why newcomers are advised: keep a digital scan of every MPF document you ever receive. Even in 2026, a little bit of manual "detective work" is sometimes required to find that one rogue account from a short-lived internship.
Another pitfall is the "employer contribution" window. If you are currently employed, do not try to consolidate your active account into a different trustee while you are still at that company. Your employer has a legal obligation to pay into their chosen scheme. You are consolidating your preserved accounts (from previous jobs) into one new preserved account or into your current active one. If you’re unsure about the rules for your current role, check the Mandatory Provident Fund (MPF): Contribution Rules and Options guide to see how your current contributions are handled.
Preparing for the Future
As you settle into your consolidated financial life, you can start looking at more advanced moves. For example, did you know you can use your MPF balance as part of your "financial strength" proof when applying for certain visas or mortgages? A consolidated statement showing a significant sum is much more impressive to a bank manager than four small ones.
If you are planning to stay for the full seven years to get Right of Abode (Permanent Residency): The 7-Year Journey, your MPF will likely grow into one of your largest assets in the city. Keeping it consolidated allows you to track its growth against your other investments. When I finally hit my 7-year mark, seeing my total MPF balance in one place felt like a significant milestone in my Hong Kong journey.
Lastly, remember that the eMPF platform is also your gateway to voluntary contributions. If you find yourself with extra HKD at the end of the month, putting it into a TVC account via the eMPF platform is often a better move than leaving it in a low-interest savings account. When you eventually need to move that money abroad, you can use Wise to ensure you get the mid-market rate, but while it's in Hong Kong, let the MPF tax advantages work for you.
Summary Checklist for Consolidation
To make this as painless as possible, follow this checklist. I’ve done it, and while it takes an afternoon of focus, the peace of mind is worth it.
- Download iAM Smart: Ensure you have the "+" version for digital signatures.
- Register for eMPF: Log in and let the system "discover" your accounts.
- Audit the List: Check for name mismatches or missing accounts from old jobs.
- Pick your Winner: Choose the trustee with the best funds and lowest fees.
- Hit Consolidate: Check the boxes and sign the digital form.
- Set a Reminder: Check back in 14 days to ensure the units have been purchased in your new account.
- Download the Statement: Keep a copy for your records, especially for Taxes for Expats if you have foreign reporting obligations.
The "Hong Kong shuffle" is a real thing—we change jobs, we change apartments, and we change our minds. But your retirement shouldn't be shuffled. Take control of your MPF today so you can spend more time enjoying the city and less time hunting for lost passwords.
Disclaimer
This guide is for informational purposes only and does not constitute financial, legal, or tax advice. The MPF system and eMPF platform rules are subject to change by the Mandatory Provident Fund Schemes Authority (MPFA). Always consult with a certified financial planner or tax professional regarding your specific situation, especially if you have tax liabilities in multiple jurisdictions.