Declaring Permanent Departure to Withdraw MPF: Process and Forms
Navigating the final exit from Hong Kong often feels like a full-time job in itself, especially when you are staring down the administrative maze of the Mandatory Provident Fund (MPF) system. I remember the sheer exhaustion of my final weeks in the city, trying to balance packing boxes with the dread of a rejected claim. This guide simplifies that process, ensuring you can successfully declare permanent departure and reclaim your hard-earned savings.
The Foundation of Permanent Departure Claims
The most important thing to understand before you even pick up a pen is that the Hong Kong government views "permanent departure" as a terminal event for your financial residency. This isn't just about moving to another city for a few years with the intent to return; it is a formal declaration that you are leaving Hong Kong to reside in another place with no intention of returning as a permanent resident in the foreseeable future. If you have spent years navigating the Mandatory Provident Fund (MPF): Contribution Rules and Options you know that this money is strictly guarded, and the authorities do not release it lightly.
The Once in a Lifetime Rule
In the eyes of the Mandatory Provident Fund Schemes Authority (MPFA), you are generally allowed to claim early withdrawal on the grounds of permanent departure only once. This is a crucial point that many expats overlook. If you leave in 2026, withdraw your funds, and then find yourself back in a Hong Kong office three years later, you cannot use the "permanent departure" reason ever again. Your new MPF contributions will be locked away until you reach the age of 65.
Many people struggle with this because they treat their first withdrawal like a travel fund, only to return to the city and realize they’ve forfeited their right to early access for their second stint. It’s a policy designed to prevent people from "churning" their retirement savings every time they change jobs or move across the border to Shenzhen. Before you commit, make sure this truly is your major departure.
Defining Your Destination
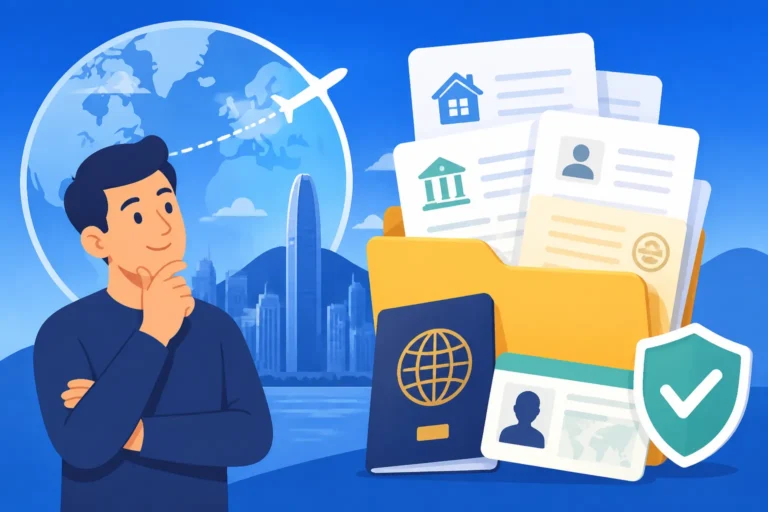
You must provide "satisfactory evidence" that you are permitted to reside in a place outside of Hong Kong. This isn't as simple as showing a one-way flight ticket to Bali. The trustees want to see that you have the legal right to stay where you are going. This could be a permanent residency visa, a long-term work permit, or even a foreign passport that allows indefinite stay.
If you are moving to a country where you don't yet have a long-term visa, you might face a "chicken and egg" scenario. The trustee won't release the funds without proof of residency, but you might need those funds to establish your new life. In these cases, documentation from your new employer or a lease agreement in your destination country can sometimes help, but the standard for "permanent" is high. This is where Leaving Hong Kong Financially Prepared: Taxes, Banks, and MPF becomes your roadmap for timing your exit.
Essential Paperwork and the Statutory Declaration
Once you’ve accepted that you are making a permanent break, the mountain of paperwork begins. The central document for this entire process is the Form MPF(S) – P(C). This is the "Claim Form for Payment of MPF Accrued Benefits on Grounds of Permanent Departure from Hong Kong." You can download this from the MPFA website or your specific trustee’s portal.
Mastering Form MPF(S) – P(C)
The form itself is relatively straightforward, but the margins for error are razor-thin. You will need to provide your personal details exactly as they appear on your HKID. If you have changed your name or if there is a typo in your trustee’s database, you need to fix that before submitting the claim.
You will also need to specify how you want to receive your funds. While many people choose a HKD check, if you are already overseas, this can be a nightmare to deposit. Tools like Wise are invaluable here because they allow you to receive the final balance into a multi-currency account, avoiding the predatory exchange rates that local banks often slap on outgoing international transfers.
The Statutory Declaration Oath
This is the part that feels most "official." You cannot just sign the claim form; you must make a formal statutory declaration. This is a legal statement made in front of a Commissioner for Oaths at one of the many Home Affairs Enquiry Centres, or a Notary Public. If you are doing this in Hong Kong, the Home Affairs Enquiry Centres provide this service for free, but you usually need to book a slot or show up very early.
During the declaration, you are essentially swearing under the Oaths and Declarations Ordinance that you are leaving Hong Kong for good. It is a criminal offense to make a false statement here. If you are already outside of Hong Kong, you must do this at a Hong Kong Overseas Consulate or in front of a Notary Public who is recognized by the HK government. This often requires an extra layer of "apostille" or legalization, which can add weeks to your timeline. Finding Statutory Declaration for Permanent Departure: Where to Find a Commissioner in your neighborhood is a task you should tick off at least a month before your flight.
The BNO Complication and Travel Documents
We have to talk about the elephant in the room: the British National (Overseas) passport. Since early 2021, the Hong Kong government and the MPFA have officially stated that the BNO passport is not recognized as a valid travel document or proof of identity for MPF withdrawal. This has created a massive hurdle for many departing expats and locals alike.
Navigating Identity Proof
If you are moving to the UK on a BNO visa, you cannot simply present your BNO passport to your trustee and expect a payout. They will reject it. To successfully withdraw your funds, you generally need to provide alternative evidence of your right to reside in the UK. This could be a letter from the UK Home Office confirming your visa status, a National Insurance number, or a long-term utility bill and rental agreement once you have actually arrived.
This policy has forced many to wait until they have physically moved and established a "paper trail" in their new country before they can even apply for their MPF. It’s a frustrating delay, but knowing this ahead of time prevents the shock of an immediate rejection letter. You will need to rely on your personal savings or services like Wise to manage your initial relocation costs while your MPF remains "on ice" in Hong Kong for those first few months.
Providing Valid Evidence
For those not moving on a BNO visa, the process is smoother but still requires precision. You will need to submit a copy of your departure record (the "exit" stamp or the e-channel record is no longer enough) and your visa for the destination country. Trustees are increasingly looking for "entry" proof into the new country.
If you are moving to your home country (where you hold a passport), the process is simpler. Your foreign passport acts as your proof of right to reside. However, the trustee still needs to see that you have actually left. Some trustees require a copy of your final boarding pass or a letter from your HK employer stating that your contract has ended and you are repatriating. Ensuring you have What Happens to My Employer MPF Contributions if I am Terminated? clarified with your HR department can help gather these secondary proofs.
Coordination with Trustees and the eMPF Platform
A common headache for long-term expats is having multiple MPF accounts scattered across different trustees. If you’ve worked for three different companies over seven years, you likely have three separate pots of money. Each one requires its own set of forms and its own statutory declaration.
Consolidating Your Savings
Before you even think about the departure forms, use the eMPF platform to see exactly where your money is. It is ten times easier to file one claim than four. I always advise people to start Consolidating Multiple MPF Accounts via the eMPF Platform at least three to six months before their departure date. Once all your funds are under one trustee—say, HSBC or Manulife—you only have to deal with one administrative desk and one set of rules.
Consolidation takes time. It’s not an instant transfer. You have to wait for the old trustee to sell your units, transfer the cash, and the new trustee to buy units in your chosen funds. If you try to do this while also filing for permanent departure, the system can glitch out because there is an "active instruction" on the account. Clean up your accounts first, then declare your departure.
Dealing with "Off-boarding" Fees
While there are technically no "fees" for withdrawing your MPF, you are at the mercy of the market. Your units will be sold on a specific day once your paperwork is processed. In a volatile market, the value of your account could shift by 2-5% between the time you sign the papers and the time the check is cut.
Additionally, be aware of how the trustee handles the final payment. Some will only mail a physical check to a Hong Kong address. If you’ve already moved to Spain, who is going to pick up that check? You might need to appoint a "proxy" or ensure your bank account remains open long enough to handle a local transfer. This is another area where having a digital-first solution can save you from a logistical nightmare.
| Document Required | Purpose | Where to Get It |
|---|---|---|
| Form MPF(S) – P(C) | Primary Claim Form | MPFA Website / Trustee |
| Statutory Declaration | Legal oath of departure | Home Affairs Enquiry Centre |
| Passport/Visa | Proof of residency abroad | Your Home Country / Consulate |
| HKID Copy | Identity verification | Personal |
| IR56G Form | Tax clearance proof | Your Employer / IRD |
| Departure Proof | Confirmation of exit | Airline / New Landlord |
Tax Clearance and Financial Integration
You cannot simply take your MPF and run. The Inland Revenue Department (IRD) wants their cut of your final salary before you vanish into the sunset. In Hong Kong, this is known as "Tax Clearance." Your employer is legally required to withhold your last month's salary until you produce an IR56G form or a "Letter of Release" from the IRD.
The Role of the IR56G
When you notify your employer you are leaving Hong Kong, they will file a form with the IRD. You then need to visit the Revenue Tower in Wan Chai (or handle it online via eTax) to settle your final tax bill. The trustee will often ask if you have cleared your tax obligations. While the MPF itself is generally tax-free in Hong Kong, failing to settle your salaries tax can lead to "stop orders" at the airport or delays in processing your financial exits.
For many expats, the tax implications don't end at the HK border. If you are moving back to a high-tax jurisdiction like the US or UK, that lump sum MPF payout might be viewed as taxable income in your new home. This is where a service like Taxes for Expats becomes essential. They can help you figure out if your MPF withdrawal qualifies as a foreign pension distribution and how to report it without getting double-taxed. Understanding the Hong Kong Tax Guide for Expats: Salaries Tax and Filing (2026) will help you budget for that final tax bill.
Managing the Payout
Once the trustee approves your claim, you will receive your payout. This usually takes between 30 to 60 days from the date of submission, assuming everything is perfect. If you are receiving a few hundred thousand Hong Kong dollars, you don't want that sitting in a zero-interest HKD account while you are paying for a new life in Euros or Pounds.
Using Wise to move these funds is the most realistic way to preserve your capital. Traditional banks will take a "spread" on the exchange rate that can cost you thousands of dollars on a large MPF payout. By receiving the HKD and converting it at the mid-market rate, you ensure that your retirement savings actually make it to your new destination intact. You should also check Everyday Budgeting in HK: Cost of Living Benchmarks (2026) to estimate how much "buffer" cash you need to keep in HKD for those final utility bills before the MPF arrives.
Life After Withdrawal: Can You Ever Come Back?
A question I get asked constantly is: "If I take my MPF now, am I banned from Hong Kong?" The answer is a resounding no. Withdrawing your MPF has no impact on your visa status or your right to work in Hong Kong in the future. It is a financial decision, not an immigration one.
Returning to the Workforce
If you decide to return to Hong Kong in two years because a dream job opened up, you will simply start a new MPF account. You will be treated as a "new joiner." Your previous withdrawal is a closed chapter. However, as mentioned earlier, you won't be able to withdraw this new money early for departure. You'll be waiting until 65.
This is why some people choose not to withdraw their MPF at all. If your balance is small and you think you might be back in a few years, leaving the money in a preserved account allows it to keep growing (or shrinking, depending on your fund choice) without the administrative headache of the permanent departure process. If you aren't sure, read about How to Transfer Your MPF When Changing Jobs to see if keeping a preserved account is a better fit for your nomadic lifestyle.
Final Audit Risks
The MPFA does occasionally audit "permanent departure" claims. If you withdraw your funds and the authorities find you back in Hong Kong working a month later, they may investigate whether the initial declaration was fraudulent. Usually, as long as there was a genuine intent to leave at the time of the declaration, you are safe. But if you are just "visa-running" to get your cash, you are playing with fire. The legal consequences of a false statutory declaration are severe, including potential jail time. Always ensure your paper trail—the one-way ticket, the terminated lease, the Tax Clearance Letter (IR56G): What You Need Before Leaving HK—all point to a genuine exit.
Specific Scenarios and Troubleshooting
Even with the best preparation, things can go wrong. The most common point of failure is the "Evidence of Right to Reside." If you are moving to a country with a "Visa on Arrival" policy or a digital nomad visa that is only granted after you arrive, your trustee will likely stall your claim.
The "Stuck in Limbo" Scenario
If you find yourself in this situation, the best strategy is to wait until you have arrived in your destination and obtained a local residency card or a long-term lease. You can then mail the documents back to Hong Kong. You don't have to be physically present in the city to file your MPF claim, provided you have a way to get your statutory declaration notarized locally.
I’ve known expats who moved to Southeast Asia and had to wait four months until their business visa was finalized before their HK trustee would release their funds. During that time, they used Wise to manage their existing HKD savings. It requires patience, but the money isn't lost; it’s just delayed. You might also want to check if Can Employers Deduct MPF from Severance Payments (Offsetting)? applies to you, as this could change the total amount you expect to receive.
Common Errors in Forms
Double-check the "Reason for Payment" section. Ensure you have checked the box for "Permanent Departure" and not "Early Retirement" or "Small Balance." These are different legal categories with different requirements. Also, ensure your witness (the Commissioner for Oaths) has clearly stamped and signed every page where their signature is required. If a stamp is blurry, the trustee's "compliance" department will likely reject the whole packet. It feels petty, but in the world of Hong Kong finance, the "chopping" (stamping) of documents is sacred.
Disclaimer
The information provided in this guide is for educational and informational purposes only and does not constitute legal, financial, or tax advice. MPF regulations and government policies regarding travel documents and permanent departure are subject to change by the MPFA and the Hong Kong SAR Government. You should consult with a qualified financial advisor, tax professional, or your MPF trustee to confirm the latest requirements for your specific situation.