Wise vs Bank SWIFT Transfers: Cheapest Ways to Send Money
One of the most disheartening experiences as a new expat in Hong Kong is watching your hard-earned money vanish between your local bank account and your home country. I still remember the frustration of sending my first relocation reimbursement back to London and seeing nearly a thousand Hong Kong Dollars simply disappear into the banking ether without explanation. This guide breaks down exactly why that happens and compares the heavyweights of the remittance world to save you a fortune.
The Hidden Anatomy of an International Money Transfer
When you first land in the city and finish Banking in HK: Opening Accounts, Virtual Banks, and Credit Cards, you might assume that a bank-to-bank transfer is the most secure and logical way to move your salary. However, the traditional banking world operates on a legacy system known as SWIFT (Society for Worldwide Interbank Financial Telecommunication). It is important to understand that SWIFT does not actually move money; it moves data. It is essentially a global messaging network that tells one bank to debit an account and another bank to credit one.
The problem for us expats is the "Correspondent Banking" network. If your bank in Hong Kong doesn't have a direct relationship with your bank in, say, a small town in Ohio or a regional branch in France, the money has to hop through intermediary banks. Each of these "middleman" banks takes a small bite out of your transfer, often ranging from USD 15 to USD 50 per hop. By the time the money reaches its destination, the final amount is significantly lower than what you sent, and your local HK bank often won't be able to tell you exactly how much the intermediaries will charge.
Beyond the fixed fees, there is the "Exchange Rate Spread." Most banks will tell you they offer "competitive rates" or even "zero commission." This is often a marketing sleight of hand. While they might not charge a flat fee for the service, they make their profit by offering you an exchange rate that is 2% to 5% worse than the actual mid-market rate you see on Google or Reuters. On a transfer of HKD 100,000, a 3% spread means you are effectively paying HKD 3,000 just for the privilege of converting your currency.
Navigating SWIFT Transfers via Traditional HK Banks
If you have gone through the effort of Opening a Traditional Bank Account: HSBC, Standard Chartered, and BOC, you already have access to the SWIFT network. For some high-net-worth individuals or those moving massive sums (upwards of HKD 500,000), the security and "Premier" status of a traditional bank might feel more comfortable. However, for the average monthly remittance, the costs are prohibitive.
In Hong Kong, most traditional banks charge an outward remittance fee. This is usually split into two parts: a local handling fee (typically HKD 150 to HKD 250) and a cable charge. If you choose to pay all fees upfront (the "OUR" instruction), you could be looking at HKD 400 or more just to start the process. If you choose the "SHA" (shared) or "BEN" (beneficiary) options, the fees are deducted along the way, leading to that "disappearing money" phenomenon I mentioned earlier.
The speed of SWIFT is another pain point. Because the money relies on the operating hours of multiple banks across different time zones, a transfer can take anywhere from three to five business days. If there is a typo in the IBAN or a missing intermediary BIC code, your money can get stuck in "limbo" for weeks.
When Traditional Banks Actually Make Sense
Despite the costs, there are specific scenarios where using your traditional HK bank is the safer bet. If you are making a down payment on a property abroad, many title companies or solicitors require the funds to come from a verified traditional financial institution to satisfy stringent Anti-Money Laundering (AML) checks. In these cases, the paper trail provided by a major bank like HSBC is often more easily accepted than a digital-first platform.
Furthermore, if you are a "Premier" or "Priority" customer, your bank may waive the outward remittance fees entirely. However, even if they waive the HKD 200 fee, you must remain vigilant about the exchange rate spread. Often, the "free" transfer for VIP customers still includes a significant markup on the currency conversion, which could still make it more expensive than using Wise.
The Role of Virtual Banks in Remittances
Lately, the rise of virtual banks has changed the landscape slightly. When comparing Mox vs ZA Bank: Which Virtual Bank is Better for Everyday Spending?, you will notice that these institutions often partner with third-party providers to offer cheaper transfers. While they are more convenient and have better apps than the "Big Three" banks, they still generally lag behind dedicated remittance services in terms of pure currency exchange transparency.
The Wise Alternative: How Digital Platforms Disrupt the System
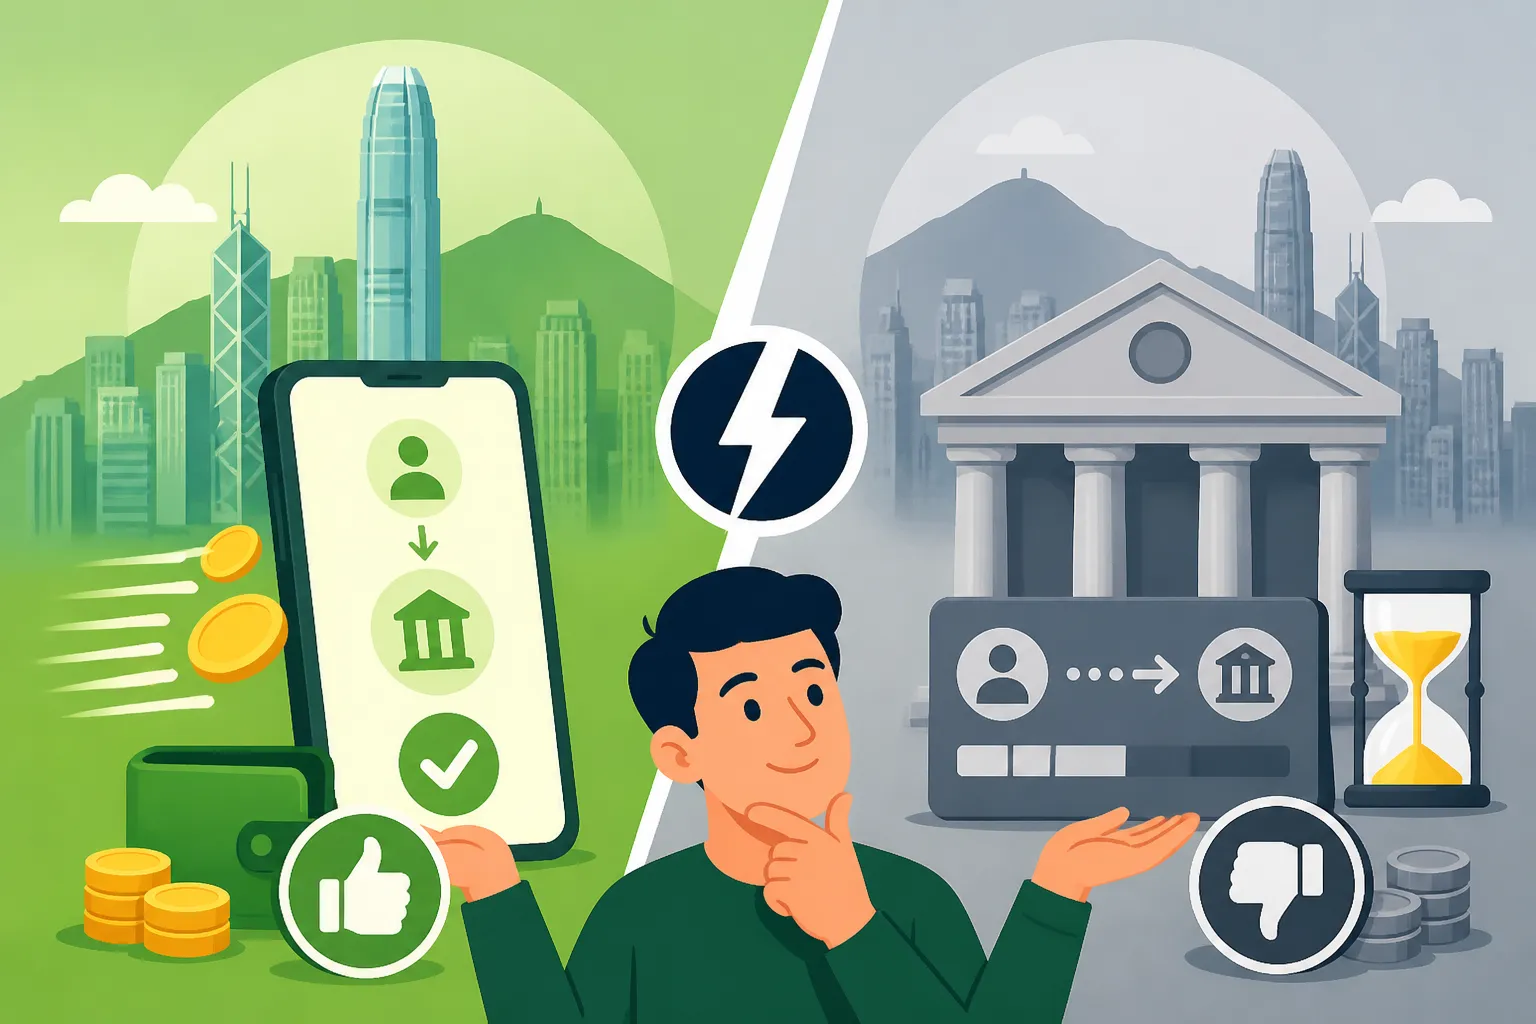
Wise has become the go-to for the Hong Kong expat community for one primary reason: transparency. Unlike the SWIFT system, Wise uses a "peer-to-peer" or local-to-local model. When you want to send HKD to the UK, you aren't actually sending your Hong Kong Dollars across the ocean. Instead, you send your HKD to Wise's local bank account in Hong Kong. Once they receive it, they send the equivalent amount in GBP from their local account in the UK to your recipient.
This method completely bypasses the correspondent banking network and the associated "hops." Because no money actually crosses international borders in the traditional sense, there are no intermediary bank fees. This is why Wise can often complete a transfer in minutes or hours, rather than days. It’s a bit like a global game of ledger balancing that saves us a massive amount of money.
The most significant advantage of Wise is the use of the "Mid-Market Rate." This is the real exchange rate—the one banks use to trade with each other. They charge a small, transparent percentage fee on top of this rate, which is clearly displayed before you hit "send." For most expats, knowing exactly how much will land in the home account down to the last cent is a huge relief for Everyday Budgeting in HK: Cost of Living Benchmarks (2026).
Setting Up and Funding Your Account
To get started with Wise in Hong Kong, you will need to provide Address Proof Requirements for Opening a Bank Account in HK. This usually involves a utility bill or a bank statement from your local HK institution. Once verified, you can fund your transfers using the Faster Payment System (FPS): How to Use It for Rent and Bills. FPS is a godsend for expats; it allows you to send money from your HK bank to Wise instantly and for free, 24/7.
One thing to watch out for is the funding method. Using a credit card to fund a Wise transfer in Hong Kong will often trigger "Cash Advance" fees from your bank, which are exorbitant. Always use a bank transfer or FPS to keep your costs at the absolute minimum. I have found that a transfer initiated on a Tuesday morning in Hong Kong often hits my European account by Tuesday afternoon.
The Multi-Currency Account Feature
For those who travel frequently or have financial obligations in multiple countries, the Wise multi-currency account is an essential tool. You can hold over 40 currencies and get local bank details (like a UK Sort Code or a US Routing Number) without being a resident of those countries. This is incredibly helpful when you need to receive a tax refund from your home country or pay a recurring bill without the constant conversion fees.
Comparing the Costs: Real-World Comparison Table
To give you a clearer picture, let's look at a hypothetical scenario. Imagine you are sending HKD 50,000 from your account in Hong Kong to a bank account in Australia. The figures below are estimates based on typical 2026 market conditions and fee structures.
| Feature | Traditional HK Bank (SWIFT) | Wise (Transfer) |
|---|---|---|
| Exchange Rate | 2% – 4% Markup (Hidden) | Real Mid-Market Rate |
| Upfront Fee | HKD 150 – HKD 400 | Approx. HKD 230 – 280 |
| Intermediary Fees | Possible (USD 15 – 50) | None |
| Total Cost (Est.) | HKD 1,200 – 2,200 | HKD 230 – 280 |
| Transfer Speed | 2 – 5 Business Days | Instant to 24 Hours |
| Predictability | Low (Final amount varies) | Guaranteed (To the cent) |
As you can see, for a standard monthly transfer, the savings are not just a few dollars—they represent a significant portion of your Cost of Living in Central vs New Territories: A Practical Comparison. If you are sending money home every month for a year, using a traditional bank could cost you the equivalent of a weekend trip to Thailand in fees alone.
Compliance, Tax, and Reporting for Remittances
When you start moving large sums of money out of Hong Kong, it is inevitable that you will trigger some compliance flags. This is normal and nothing to be afraid of, but you should be prepared. Hong Kong has strict Anti-Money Laundering (AML) and Counter-Terrorist Financing (CTF) regulations. If you suddenly send HKD 200,000 home, Wise or your bank may ask for a "Source of Wealth" or "Source of Funds" document.
Keep your payslips and your employment contract handy. A simple PDF of your latest salary slip is usually enough to satisfy these requests. If the money is from a property sale, have the sale and purchase agreement ready. The key is to be proactive; if a transfer is "pending," check your email immediately to see if the provider is requesting more information.
Tax Implications of Sending Money Home
One of the biggest misconceptions among expats is that sending money "home" is a tax-free event. While Hong Kong does not have a capital gains tax or a tax on outgoing remittances, your home country might have different ideas. For example, if you are a US citizen, you must be aware of Double Taxation Relief: US Citizens Filing Taxes in Hong Kong. Large transfers into US accounts can sometimes trigger "gift tax" inquiries or require specific disclosures on your FBAR (Foreign Bank and Financial Accounts) filings.
Using services like Taxes for Expats can be a lifesaver here. They specialize in helping Americans and other nationalities navigate the complex intersection of foreign income and domestic reporting. If you are moving a significant portion of your net worth, consulting with Taxes for Expats ensures that you aren't accidentally creating a massive tax liability back home just by trying to save on transfer fees.
Managing Your Final Exit from Hong Kong
If you are planning on leaving the city permanently, the stakes are even higher. You will need to secure a Tax Clearance Letter (IR56G): What You Need Before Leaving HK before your employer can release your final paycheck. Once that final, often large, sum hits your account, you will want the most efficient way to move it. Many expats choose to keep their Wise account active even after leaving Hong Kong to manage any trailing Sending Money Home: International Remittances and Forex Rates needs, such as MPF withdrawals or security deposit refunds that come through months later.
Making the Final Decision: Which Should You Use?
So, which should you choose for your next transfer? It essentially boils down to three factors: the amount, the urgency, and your status with your bank.
For 95% of expat scenarios—paying student loans, sending money to family, or topping up a savings account—Wise is the clear winner. The combination of the mid-market rate and the speed provided by the Faster Payment System (FPS): How to Use It for Rent and Bills makes it nearly impossible for traditional banks to compete.
However, do not count the traditional banks out entirely. If you are moving millions of dollars for a property purchase, or if you are an HSBC Premier customer whose "Total Relationship Balance" grants you "Global Transfers" with zero fees and a narrowed spread, the convenience of staying within one ecosystem might outweigh the slight cost difference. Just be sure to do the math on the exchange rate; "zero fee" is never truly free if the rate is poor.
Finally, keep an eye on Digital Payments in HK: Octopus, AlipayHK, PayMe, and WeChat Pay as well. While these are primarily for local spending, some are beginning to dabble in cross-border remittances to mainland China and Southeast Asia. For those specific corridors, local fintech players might occasionally offer promotional rates that even beat the international giants.
Regardless of which path you choose, the golden rule of expat finance in Hong Kong is to never accept the first rate you are offered. Take five minutes to compare the bank's "Live Rate" against the Wise calculator. That five-minute habit has saved me enough to cover my utilities for several months over the years, and in a city as expensive as Hong Kong, every dollar counts.
Disclaimer
This guide is for informational purposes only and does not constitute financial, legal, or tax advice. Exchange rates and bank fees are subject to frequent change. Always perform your own due diligence and consult with a qualified professional, such as the team at Taxes for Expats, regarding your specific tax residency and reporting obligations before making large international transfers.