Faster Payment System (FPS): How to Use It for Rent and Bills
The struggle of managing a thick stack of paper bills while trying to find an ATM that doesn't have a twenty-person queue in Central is a rite of passage for every new arrival. I remember my first month in Sai Ying Pun, sweating through my shirt while trying to figure out how to pay my landlord without a checkbook. This guide solves the mystery of the Faster Payment System (FPS), turning your smartphone into the ultimate tool for conquering Hong Kong's monthly overheads.
The Magic of Instant Transfers in the Vertical City
When I first moved here, I was shocked by how many things still relied on physical checks or standing in line at a 7-Eleven. Then came the Faster Payment System, or FPS, launched by the Hong Kong Monetary Authority. It completely disrupted the way we handle Everyday Budgeting in HK: Cost of Living Benchmarks (2026) by allowing real-time, 24/7 transfers between different banks and even digital wallets. Whether you are splitting a dim sum bill in Mong Kok or paying a high-stakes rent deposit, FPS is the infrastructure that makes it happen instantly.
The Technology Behind the Scenes
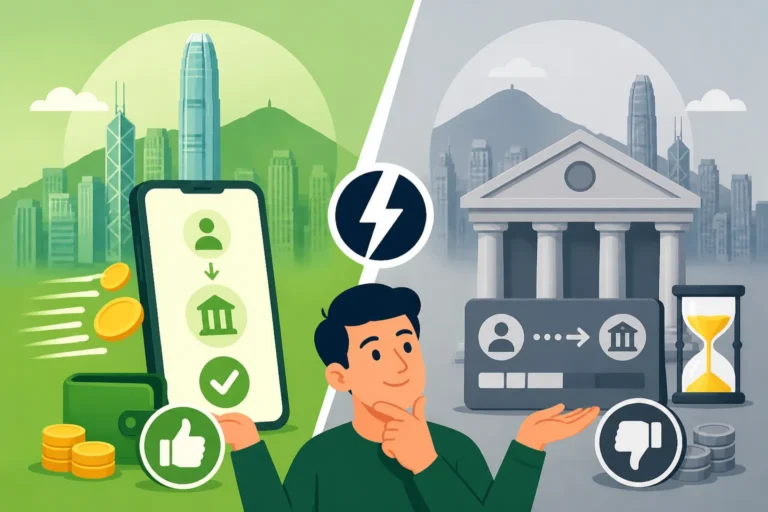
FPS isn't just another app you download; it’s a backend system that connects almost every financial institution in the territory. Unlike the old days when a transfer from HSBC to Standard Chartered could take two business days, FPS happens in seconds. It uses a "Proxy ID" system, which means you don't need to memorize long, complicated bank account numbers. Instead, you link your bank account to your mobile phone number, your email address, or a unique FPS ID.
The beauty of this system is its interoperability. In many countries, you’re stuck within a single ecosystem like Venmo or Zelle. In Hong Kong, FPS bridges the gap between traditional banks and Stored Value Facilities (SVFs). This means you can send money from your ZA Bank account directly to someone’s Digital Payments in HK: Octopus, AlipayHK, PayMe, and WeChat Pay account without any friction. For an expat, this removes the "silo" feeling of local banking and makes your funds incredibly liquid.
Why Expats Specifically Need to Master This
The transition to Hong Kong life is often defined by administrative hurdles. You’ll quickly find that many local services—like your yoga instructor in Sheung Wan or a niche grocery delivery service—prefer FPS because it has no transaction fees for the recipient. If you rely solely on credit cards or cash, you’ll find yourself excluded from the most convenient local services. Moreover, when you’re Banking in HK: Opening Accounts, Virtual Banks, and Credit Cards, setting up FPS is usually the very first thing the bank teller will suggest, and for good reason.
Many newcomers find FPS to be a lifesaver during the first few months of relocation. When you don't have a local credit history, getting a credit card can be a slow process. FPS allows you to function like a local from day one, provided you have a local bank account. It’s the primary way I pay my domestic helper, my daughter’s tutor, and even my share of the "AA" (split) bill after a night out in LKF.
Getting Started: Your Digital Identity in HK Banking
Setting up FPS is surprisingly straightforward, but there are a few nuances that can trip you up if you aren't careful. You’ll need a local bank account and a Hong Kong mobile number. If you haven't secured these yet, make that your priority. Most banking apps will prompt you to register for FPS the moment you log in for the first time. It is a one-time setup that anchors your financial presence in the city.
Registration Step-by-Step
To register, log into your mobile banking app—be it a traditional giant like HSBC or a modern virtual bank like Mox. Look for a menu item labeled "FPS Settings" or "Register FPS." You will be asked which Proxy ID you’d like to use. I highly recommend using your Hong Kong mobile number as your primary proxy. This is because most people you interact with will already have your number saved in their contacts, making it incredibly easy for them to send you money.
Once you select your proxy, the bank will send you an OTP (One-Time Password) to verify the link. A crucial tip: you can link multiple banks to the same phone number, but you must choose one as your "Default Bank." This is the account that will receive funds if someone simply enters your phone number without specifying a bank. If you are using services like Wise to manage your international transfers, having a clearly defined default local bank account makes the internal movement of your HKD much smoother.
Choosing Your Proxy ID: Mobile vs Email vs FPS ID
While the mobile number is the most common proxy, the email proxy is excellent for privacy. If you’re selling a second-hand sofa on a Facebook expat group and don't want to give out your phone number, the email proxy is a perfect middle ground. The "FPS ID" is a random string of numbers generated by the system, primarily used by businesses or for more formal transactions.
I suggest registering both your mobile and your email. This gives you flexibility depending on who you are dealing with. For example, when I deal with my landlord, I use my FPS ID to keep things formal and easily traceable in my records. For friends, it's always the mobile number. Just remember that if you change your phone number (common for expats who travel frequently or switch providers), you must update your FPS registration immediately to avoid your money being sent to the person who inherits your old number.
Paying Rent with FPS: A Game Changer for Landlord Relations
In the past, rent was a stressful monthly ritual involving physical checks or tedious "Add New Payee" steps on a desktop browser. Now, Step-by-Step Guide to Renting an Apartment in Hong Kong involves a much simpler payment flow. Most landlords, especially the younger or more tech-savvy ones, will provide you with an FPS ID or a mobile number at the start of your tenancy.
Security and Transaction Limits
One of the first things you’ll notice is that banks have "Small Value Payment" limits for FPS, usually capped at HKD 5,000 or 10,000 per day for unregistered payees. Obviously, your rent in Hong Kong is likely much higher than that. To pay rent via FPS, you will need to increase your daily transfer limit within your banking app, often using your physical security device or face ID.
I learned the hard way that you should set this up a few days before rent is due. Some banks have a 24-hour cooling-off period when you increase your daily limit for security reasons. Once your limit is set—say to HKD 50,000—you can send the full rent amount in a single transaction. Always double-check the recipient's name. When you enter an FPS ID or phone number, the bank will show a partially masked name (e.g., L* K*** W**). Verify this matches your landlord’s name on the lease before hitting "Confirm."
Verification and Instant Receipts
The "instant" nature of FPS is its greatest strength. The moment you hit send, the money leaves your account and arrives in your landlord’s. The banking app will generate a confirmation screen with a reference number. I always take a screenshot of this and WhatsApp it to my landlord immediately. It serves as an instant receipt and prevents any "I haven't received it yet" disputes.
For those of us who are meticulously organized (or just paranoid about late fees), most banking apps allow you to schedule FPS payments. You can set it to transfer your rent on the 1st of every month automatically. This is a huge relief when you’re traveling or caught up in a busy work week. Just ensure your account is sufficiently funded, as a bounced FPS scheduled payment can sometimes lead to annoying bank charges.
Utilities and Taxes: Taming the Paper Dragon
The most satisfying use of FPS is paying utility bills. In Hong Kong, your mailbox will inevitably be stuffed with bills from CLP (electricity), Towngas, or the Water Supplies Department. Almost all of these bills now come with an "FPS QR Code" printed at the bottom or included in the e-bill. This turns a five-minute data entry chore into a five-second scan.
Using the QR Code Scan Function
Open your banking app and look for the "Scan to Pay" icon. Point your camera at the QR code on your bill. The app will automatically populate the biller name, the exact amount due, and your customer account number. There is zero room for typos. I can’t tell you how many times I used to mis-type my Setting Up Utilities: Electricity, Water, Gas, and Broadband in HK account numbers in the pre-FPS era, leading to hours of phone calls with customer service to track down my "lost" payment.
This QR system works for:
- Electricity (HK Electric and CLP)
- Gas (Towngas)
- Water (WSD)
- Government Rates and Land Rent
- Broadband and Mobile bills (PCCW, SmarTone, etc.)
Handling Taxes and Government Fees
When it comes to the tax man, FPS is equally efficient. Whether you are Filing BIR60 via eTAX: Step-by-Step Guide for Expats or paying your final tax bill, the Inland Revenue Department (IRD) provides a QR code. Even firms like Taxes for Expats will tell you that keeping a clean, digital trail of your local tax payments is essential for your global compliance.
You can even use FPS to How to Pay Tax by Telephone, eTAX, or ATM in Hong Kong by scanning the code on your demand note. It is the fastest way to ensure your payment is recorded before the deadline, especially during the frantic "Tax Season" in January and April. The system also supports paying for government services like HKID replacement fees or traffic fines (though hopefully, you won't need that last one too often).
Comparing Payment Methods in Hong Kong
| Feature | FPS (Faster Payment) | Traditional Bank Transfer | Digital Wallets (PayMe/Alipay) |
|---|---|---|---|
| Speed | Instant (Real-time) | 1-2 Business Days | Instant |
| Fees | Free for Personal Use | Often Free, but can incur fees | Free (mostly) |
| Biller Support | Extremely High (All Utilities) | Moderate | High (Retailers) |
| Daily Limits | Adjustable (up to 1M+) | High | Lower (usually < 100k) |
| Ease of Use | High (QR/Phone) | Low (Account Numbers) | High (QR/Social) |
Security, Limits, and the 'Oops' Factor
While FPS is incredibly convenient, its "instant and irreversible" nature means you need to be sharp. Unlike a credit card transaction, you cannot easily "chargeback" an FPS payment if you make a mistake. If you send HKD 5,000 to the wrong phone number, getting that money back relies entirely on the honesty of the recipient or a very tedious legal process through your bank.
Sending Money to the Wrong Person
The most common error is a "fat-finger" typo in a phone number. To mitigate this, always use the "Contact List" integration in your banking app. This allows you to pick a recipient directly from your phone book, ensuring the number is correct. Also, pay close attention to the "Confirmation" screen. The bank will display the registered name of the recipient. If the initials don't look right, stop immediately.
If you do make a mistake, contact your bank’s customer service hotline right away. They can initiate a "recovery of misdirected funds" request. However, the bank cannot forcibly take the money back from the recipient’s account without their consent. This is why many expats use Linking Your Bank Account to AlipayHK and PayMe as an extra layer of verification, as those apps often show a profile picture of the recipient.
Scams and Phishing Alerts
As with any popular payment system, scammers have taken notice. A common tactic is the "overpayment scam," where someone "accidentally" sends you money via FPS and asks you to send it back to a different account. Never do this. If you receive an unexpected FPS transfer, tell the person to contact their own bank to initiate a formal reversal.
Be wary of SMS messages or emails that look like they’re from your bank asking you to "Update your FPS details." Banks will never ask for your login credentials via a link. Always log in through the official app. When moving large sums, perhaps after using Wise to bring in relocation funds, be extra vigilant. The speed of FPS is a scammer’s best friend because the money can be moved through five different accounts across the globe in the time it takes you to realize something is wrong.
Navigating the Broader Ecosystem
Mastering FPS isn't just about bills; it’s about participating in the local economy. You’ll find FPS QR codes at "wet markets" in Wan Chai and at tiny street food stalls in Sham Shui Po. It has effectively bridged the gap between the "cash only" old world and the "credit card only" luxury world of Hong Kong.
Integration with Other Apps
Most digital wallets in Hong Kong are now "FPS-enabled." This means your PayMe balance can be topped up via FPS, or you can send money from your bank directly to someone’s AlipayHK wallet using their mobile number. This level of integration is what makes the Hong Kong fintech scene so robust compared to many Western countries.
If you are an entrepreneur or freelancer, you can even generate your own FPS QR codes to get paid by clients. It removes the awkwardness of sharing bank details and ensures you get paid instantly. Many expats who are Starting a Business in HK: Company Incorporation and Freelancing find that offering FPS as a payment method significantly improves their cash flow, as local clients are much more likely to pay an instant FPS "request" than a traditional invoice.
Final Practical Advice for New Arrivals
When you first land, the number of "essential" apps can feel overwhelming. My advice is to focus on one primary banking app and register your FPS there immediately. Don't worry about registering at five different banks. One solid "Default Bank" for FPS is all you need to handle 99% of your life here.
Also, keep an eye on your transaction history. Because FPS is so easy, it’s very easy to "micro-spend" your way through your budget. Coffee here, a taxi there—it all adds up. I find it helpful to review my FPS history once a week to ensure I’m staying on track with my monthly goals. With this system in your pocket, you’ve conquered one of the biggest hurdles of living in this incredible, fast-paced city.
Disclaimer
This guide is for informational purposes only and does not constitute financial or legal advice. Payment systems, bank policies, and government regulations in Hong Kong are subject to change. Always verify transaction details and limits directly with your financial institution. Use of third-party apps and services is at your own risk.