Healthcare in Hong Kong: Public vs Private Systems Explained (2027)
Navigating a sudden fever in a foreign city is terrifying, especially when you are staring at a completely unfamiliar hospital system. I remember sitting in a crowded Wan Chai clinic at 2 AM, utterly confused by the triage numbers and payment queues. This comprehensive guide breaks down exactly how to master both the public and private medical systems in Hong Kong.
The Core Framework of Hong Kong Healthcare
How the Dual Healthcare System Operates
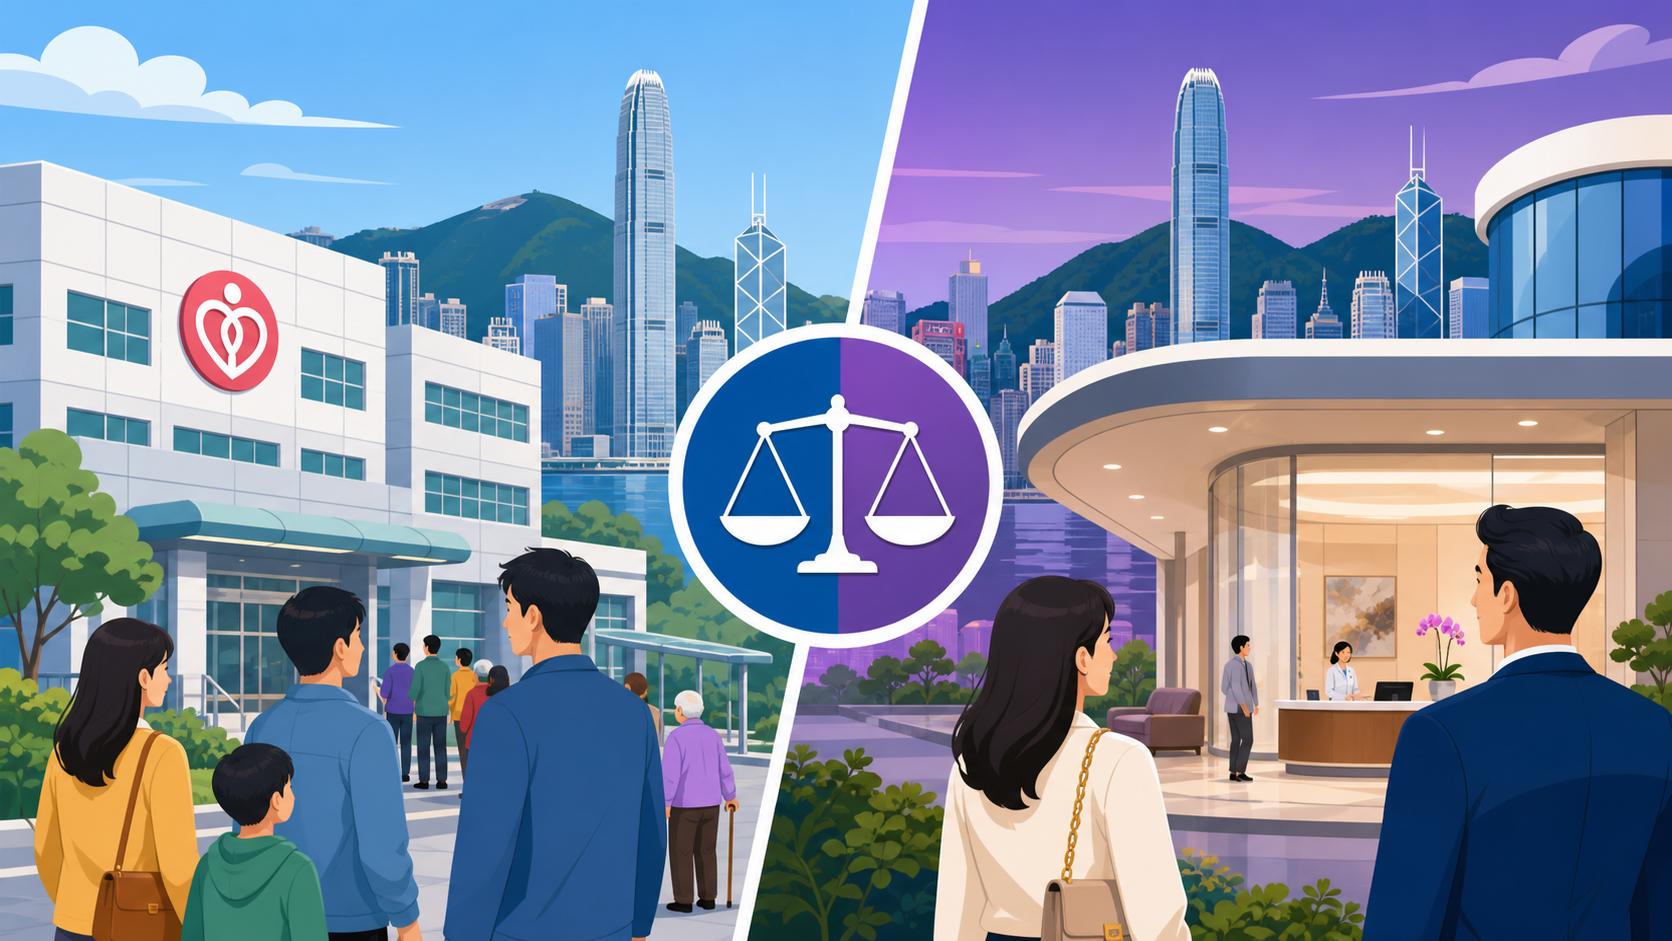
Hong Kong operates on a highly efficient, yet distinctly polarized, dual healthcare system. On one side is the heavily subsidized public sector, managed by the Hospital Authority. This network handles the vast majority of inpatient care and emergency services for the territory’s millions of residents. The medical standard here is world-class, heavily monitored, and staffed by doctors who often train at the same prestigious global institutions as their private sector counterparts. However, this system operates under immense volume, leading to an environment built purely for clinical efficiency rather than patient comfort.
Running parallel is a lucrative, expansive private healthcare sector. This side of the system is designed to provide immediate access, luxurious amenities, and personalized care—at a premium price. The private sector is dominated by standalone specialized clinics, corporate medical groups, and prestigious private hospitals that often resemble five-star hotels more than medical facilities. Expats quickly realize that while the public system is a safety net for catastrophic emergencies, the private system is where they will spend most of their time for routine illnesses, diagnostics, and preventative care to avoid the crushing wait times of the public route.
The choice between the two rarely comes down to the quality of the medical outcome, but rather the quality of the experience. In the public system, you will be treated effectively, but you will wait hours in a plastic chair, sleep in a ward with up to ten other people, and have no choice over your attending physician. In the private system, you dictate your appointment time, select your specialist by name, and recover in a private suite, provided you or your insurance can bear the financial weight.
Establishing Eligibility for Subsidized Rates
The dividing line between affordable care and staggering medical bills in the public system entirely depends on your residency status. The Hospital Authority categorizes patients into two strict groups: Eligible Persons and Non-Eligible Persons. To be an Eligible Person, you must hold a valid Hong Kong Identity Card. Once you possess this card, regardless of whether you are a permanent resident or a newly arrived expat on a temporary work visa, the doors to heavily subsidized healthcare swing wide open. A night in a public hospital ward drops to a nominal fee of roughly HKD 120, a price that covers everything from the bed to complex surgical procedures and meals.
For expats who have just landed, there is a dangerous vulnerability window. By law, you have 30 days to apply for your identity card after arriving on a valid visa. If you require emergency medical care before your card is issued, you will be classified as a Non-Eligible Person. The financial difference is jarring. A simple visit to the accident and emergency department jumps from a subsidized HKD 120 to over HKD 1,200 just to be seen by a triage nurse, while inpatient ward fees can exceed HKD 5,000 per night without factoring in surgery or medication costs. It is highly advisable to prioritize Registering Your HKID for Subsidized Public Healthcare Rates the moment your employment or dependent visa is activated.
If you find yourself in a situation where you require care while holding only your immigration application receipt, the hospital will still charge you the Non-Eligible Person rate upfront. You must retain every single receipt and discharge document. Once your official card is granted, you can return to the hospital’s billing department to retroactively claim the difference, a bureaucratic headache that involves filling out forms and waiting several weeks for a refund check to be mailed to your local address.
| Feature | Public System (Hospital Authority) | Private System |
| Primary Cost | Extremely low (Highly subsidized) | Extremely high (Market rates) |
| Wait Times (Routine) | Months to years | Same day or within days |
| Wait Times (A&E) | Hours (depending on triage) | Minimal to none |
| Doctor Selection | Assigned by shift roster | Full patient choice |
| Inpatient Amenities | Basic open wards, strict visiting hours | Private rooms, hotel-like catering |
| Language Barrier | Occasional (nurses often speak Cantonese) | Rare (fluent English is standard) |
Navigating the Hospital Authority Public Network
Registering and Booking Outpatient Services
The first point of contact for non-emergency medical issues in the public sector is the General Outpatient Clinic network. Scattered across every district in Hong Kong, these clinics handle minor illnesses, chronic condition monitoring, and basic referrals. However, securing a slot at one of these clinics is an infamous rite of passage. Walk-ins are generally not accepted for acute illnesses. Instead, the entire system relies on an automated telephone booking system or the HA Go mobile application, which operates on a strict quota basis.
Using the booking system requires strategic timing. The quotas refresh at specific intervals, and the slots are routinely snatched up within minutes by thousands of residents tapping their screens simultaneously. Many expats find themselves setting alarms for midnight or early morning just to secure a brief consultation for a persistent cough or a minor infection. The interface of the app is highly functional, but the sheer volume of demand means you must be incredibly persistent. If you fail to secure a digital slot, the only alternative is queuing outside the clinic before dawn in hopes of grabbing one of the few physical standby tickets, a reality most working professionals cannot accommodate.
Once you actually secure an appointment and arrive at the clinic, the process is relentlessly efficient. You register your identity card at a kiosk, pay your modest fee of HKD 50, and watch digital screens until your number is called. Consultations are remarkably brief, often lasting less than five minutes. The doctors are highly capable but their primary objective is to clear the waiting room, not to engage in lengthy bedside conversations. You describe your symptoms, receive a diagnosis, and are immediately directed to the pharmacy window to collect a plastic bag of pre-dispensed medications.
Accident and Emergency Triage Protocols
When you face a genuine medical crisis and call 999 or walk into a public hospital, you are immediately thrust into the Accident and Emergency triage system. The public A&E does not operate on a first-come, first-served basis. Upon arrival, a triage nurse assesses your vital signs and assigns you to one of five strict categories: Critical, Emergency, Urgent, Semi-urgent, and Non-urgent. This categorization entirely dictates whether you see a doctor in two minutes or twelve hours, and expats must adjust their expectations accordingly to survive the waiting room frustration.
If you arrive via ambulance with a suspected heart attack or severe trauma, you are classified as Critical or Emergency and will bypass the waiting room entirely. The response is immediate, aggressive, and highly specialized. However, if you walk in with a sprained ankle, a minor laceration, or a stubborn fever, you will likely be labeled Semi-urgent or Non-urgent. This is where the reality of the public system sets in. You will take a seat in a crowded, brightly lit waiting area, surrounded by the coughing public, and wait while more severe cases continuously jump the queue ahead of you.
It is vital to understand Accident and Emergency (A&E) Triage Categories in Public Hospitals because complaining to the nursing staff will not expedite your care. They are bound by protocol. We sat in the Queen Elizabeth Hospital waiting room from 8 PM until 4 AM before a doctor finally stitched the wound. You must bring a phone charger, a warm jacket because the air conditioning is notoriously freezing, and an immense amount of patience.
Specialist Wait Times and Public Ward Realities
The most significant bottleneck in the Hong Kong public healthcare system is access to specialist care. You cannot simply decide to see a public dermatologist or orthopedic surgeon; you must obtain a referral from a public general practitioner. Once you submit this referral, a triage team reviews your case and assigns you an appointment date. For life-threatening conditions like aggressive cancers, the system moves rapidly, slotting you in within weeks. However, for non-life-threatening, chronic, or routine specialist care, the waiting times are measured in years, not months.
It is entirely common to receive a letter stating your first consultation for a routine knee issue or a skin condition will take place in 80 to 100 weeks. This agonizing delay is precisely what drives middle-class locals and expats directly into the arms of the private sector. If you choose to wait and eventually require inpatient care or surgery, you will be admitted to a public ward. These wards are large, communal spaces divided only by thin curtains. Privacy is essentially nonexistent, and the environment is chaotic, with nurses constantly moving between beds, alarms beeping, and cleaning staff operating around the clock.
Furthermore, public wards enforce incredibly strict visiting hours. Spouses and family members are usually only permitted to visit for two hours in the afternoon and two hours in the evening. Outside of these windows, you are on your own. While the nurses are exceptionally skilled and the medical protocols are rigorous, the staff-to-patient ratio means you will not receive personalized attention unless your monitor indicates a crisis. If you require assistance going to the bathroom or adjusting your bed, you will have to wait until a care assistant is free from their overwhelming checklist of tasks.
The Reality of the Private Healthcare Sector
Bypassing Public Queues with Private Facilities
The defining characteristic of the private sector in Hong Kong is immediate, friction-free access to care. When expats realize they cannot wait two years for a public MRI, they turn to the network of private hospitals and imaging centers that dominate the island and Kowloon. Walking into a facility like the Matilda International Hospital on the Peak or the Hong Kong Sanatorium in Happy Valley feels more akin to entering a luxury corporate lobby than a medical institution. The air smells of polished marble, concierges guide you to plush waiting areas, and the administrative staff handle all paperwork with quiet efficiency.
This level of service extends directly to the clinical side. If you need a specialist consultation, you can often secure an appointment within a day or two. If that specialist orders an MRI or a CT scan, you simply walk down the hall to the imaging department and have it done within the hour, returning to the doctor’s office immediately after to discuss the results. This seamless integration of diagnostics and consultation eliminates the agonizing anxiety of waiting for answers, which is the primary value proposition of the private route. Exploring the Top Private Hospitals on HK Island: Matilda, Adventist, and Sanatorium is usually the first step for expats mapping out their healthcare contingency plans.
However, the financial mechanics of private hospitals require strict vigilance. They operate on a purely commercial basis. Before you are even admitted to a private room, the billing department will require a substantial credit card pre-authorization, often ranging from HKD 20,000 to HKD 50,000 depending on the expected procedure. Furthermore, private hospitals charge tiered rates based on your room class. If you choose a private room rather than a semi-private room, not only does the room rate increase, but your surgeon, anesthetist, and ward doctors will also multiply their professional fees accordingly for the exact same medical procedure.
Outpatient Clinics and General Practitioners
For everyday ailments like sinus infections, stomach bugs, or minor physical injuries, expats almost exclusively utilize private general practitioner clinics. These are located in commercial office buildings in major hubs like Central, Causeway Bay, and TST. The experience is incredibly straightforward. You call the clinic, book a time, arrive, read a magazine for ten minutes, and see a doctor who speaks flawless English and has the time to actually discuss your lifestyle, diet, and overall health in detail.
A unique aspect of the Hong Kong private clinic model is the “dispensing doctor” system. Unlike in many Western countries where the doctor hands you a written prescription to fulfill at an independent pharmacy, private clinics in Hong Kong maintain their own in-house dispensaries. After your consultation, you return to the waiting room, and the receptionist hands you your medication in small, individually labeled plastic bags. This is incredibly convenient, but it also creates a financial incentive for the clinic. The cost of the medication is bundled into your final bill, often at a significant markup compared to retail pharmacy prices.
Because of this convenience, expat-heavy districts are saturated with highly qualified medical professionals. Finding English-Speaking General Practitioners (GPs) in Central is never an issue of availability, but rather an issue of budget. A standard consultation in a premium building can easily cost HKD 1,200 to HKD 2,000 before a single pill is dispensed. Expats quickly learn to build a relationship with a specific clinic, ensuring their medical history is tracked consistently without having to navigate the fragmented records of different corporate medical chains.
Private Maternity and Specialized Care
Having a child in Hong Kong perfectly illustrates the stark contrast between the two systems. Public maternity care is highly structured, very safe, and essentially free, but it offers zero frills. Husbands are routinely ushered out outside of visiting hours, pain relief options like epidurals are sometimes limited by anesthesiologist availability, and you will labor in a shared environment. Consequently, a massive percentage of the expat population opts for private maternity care, which is heavily commercialized and sold in pre-packaged bundles.
Booking a private maternity package involves securing a bed at a private hospital months in advance by paying a non-refundable deposit. You then select a private obstetrician whose clinic you will visit for all prenatal checkups. When the time comes, your chosen doctor travels to your chosen hospital to deliver the baby. These packages cover a standard number of days in the hospital, routine newborn screening, and nursery care. However, the definition of “package” is notoriously fluid. If you require an emergency C-section, need to stay an extra night, or require specialized pediatric intervention for the newborn, the package is voided, and you are billed à la carte at exorbitant rates.
Navigating specialist care beyond maternity follows a similar path of aggressive privatization. Many private specialists do not require a GP referral; you can simply look up a leading gastroenterologist or neurologist and book directly. While this empowers the patient, it also requires you to self-diagnose to a certain degree, ensuring you are booking the correct specialist for your actual problem. The lack of a centralized gatekeeper means expats must be proactive in managing their own specialist care networks, keeping meticulous records of their own test results to share between different private doctors.
Managing Costs and Health Insurance Strategies
The Limitations of Employer Group Policies
Most expats arrive in Hong Kong clutching an employment contract that includes a “comprehensive medical benefit,” assuming this solves all their healthcare needs. This is one of the most dangerous misconceptions you can hold. Local employer group policies are notorious for their aggressive sub-limits and restrictive panel networks. A typical corporate policy might offer an outpatient clinical limit of HKD 350 per visit. When your Central-based GP charges HKD 1,200 for a consultation and medication, you are left paying the HKD 850 difference entirely out of pocket for a simple sore throat.
The situation becomes dire when applied to inpatient hospital care. Employer policies rarely offer a single, high lump-sum limit for surgeries. Instead, they break the coverage down into complex sub-categories: a limit for the surgeon, a separate limit for the operating theater, another for the anesthetist, and a strict daily cap on the hospital room rate. Because Hong Kong’s private medical fees are among the highest in the world, a complex surgery can blow through these sub-limits in a matter of days. You might have HKD 100,000 in total coverage, but if the surgeon’s fee alone is HKD 80,000 and your sub-limit for surgeons is capped at HKD 30,000, you are financially liable for the massive shortfall.
Furthermore, these policies are tied entirely to your employment. If you are diagnosed with a severe, long-term illness that prevents you from working, your employment may eventually be terminated, instantly stripping you of your medical coverage precisely when you are most uninsurable due to the new pre-existing condition. Relying solely on a basic local corporate policy is a gamble that leaves expat families exposed to catastrophic financial risk if a major health crisis occurs.
International Expat Medical Insurance
To truly leverage the private healthcare system without the constant anxiety of out-of-pocket expenses, securing top-tier private health coverage is mandatory. This is where researching Private Health Insurance Plans Beyond VHIS for Expat Families becomes a critical administrative task. Premium international policies are designed to override the petty sub-limits of local corporate plans. They offer massive annual limits, comprehensive inpatient coverage without compartmentalized caps, and the freedom to walk into any premium hospital in the territory.
A major advantage of utilizing a robust global provider like Cigna Global is their extensive direct billing network. In the event of a sudden hospitalization, the last thing you want to do is negotiate a HKD 50,000 deposit on your personal credit card. With a premium global policy, the hospital’s billing department communicates directly with the insurer. You present your card, sign a guarantee of payment form, and the administrative burden is handled entirely behind the scenes. Cigna Global policies also offer the crucial benefit of global portability, meaning if you are repatriated or move to a new posting in Singapore or Dubai, your coverage travels with you, maintaining continuous coverage for any conditions you developed while in Hong Kong.
When structuring these policies, expats must balance the premium costs by strategically utilizing deductibles. Many families choose a high-deductible international plan to cover catastrophic inpatient emergencies, while paying for minor outpatient clinic visits out of pocket. This hybrid approach ensures financial survival during a major medical crisis without paying exorbitant monthly premiums just to cover the occasional bout of the flu.
Bridging Gaps for Nomads and Freelancers
Not every expat in Hong Kong is an executive on a generous corporate package. The city hosts a thriving community of digital nomads, freelancers, and entrepreneurs who must self-fund their entire medical safety net. For these individuals, traditional local insurance can be rigid, requiring long-term contracts and local banking histories that newcomers might not possess.
Flexible, subscription-based models have emerged to fill this specific void. Providers like SafetyWing are specifically structured for the modern, borderless professional. They offer plans that can be purchased online in minutes, operate on a month-to-month basis, and provide essential medical coverage that works seamlessly across multiple countries. If a freelancer in Hong Kong decides to spend three months working from Bali, their SafetyWing policy continues to protect them without the need to renegotiate regional coverage zones.
While these nomadic policies are exceptional for catastrophic coverage and unexpected emergencies, they usually operate on a pay-and-claim reimbursement model rather than direct billing networks. This means the expat must have enough personal liquidity to pay the clinic or hospital upfront, obtain detailed medical reports and itemized receipts, and submit the claim digitally. It requires a bit more administrative legwork on the patient’s part, but the flexibility and lower barrier to entry make it an indispensable tool for non-traditional expat workers.
Pharmacies Medication and Routine Care
Navigating Registered Pharmacies versus Dispensaries
Buying medication in Hong Kong can be a confusing experience due to the visual and legal distinctions between different types of drugstores. You will frequently see major chain stores like Watsons and Mannings in every shopping mall, but you cannot assume every branch has a dispensing pharmacist. Only specific, larger branches house an actual pharmacy counter behind glass, staffed by a registered professional capable of dispensing restricted medications.
Beyond the corporate chains, the streets are lined with independent local dispensaries. You must look very carefully for the official “Rx” logo illuminated on the storefront. This specific logo signifies a Registered Pharmacy authorized by the Department of Health to dispense prescription drugs. If a store lacks this logo, it is merely a medicine company permitted only to sell basic over-the-counter remedies like lozenges, simple vitamins, and traditional medicated oils. Understanding Over-the-Counter (OTC) Medicines in HK: Watsons, Mannings, and Rx will save you from arguing with a shopkeeper who legally cannot sell you the antibiotic cream you are searching for.
Interestingly, local Registered Pharmacies often operate with a degree of flexibility that surprises Western expats. While they strictly enforce prescriptions for antibiotics and psychotropic drugs, they may dispense certain chronic medications like basic inhalers, standard blood pressure pills, or specific antihistamines without demanding a fresh doctor’s note every single time, provided you can show them your previous packaging. Additionally, the prices at independent Rx pharmacies are almost always lower than the corporate chains, and polite haggling over bulk purchases of daily supplements is common practice.
Prescription Laws and Bringing Medication
Hong Kong categorizes and regulates pharmaceutical drugs with intense strictness, and the classifications frequently differ from those in North America or Europe. What you might buy straight off the supermarket shelf in your home country might be a tightly controlled substance here. A classic example is melatonin, the popular sleep aid. In the US, it is sold next to vitamin C; in Hong Kong, it is a prescription-only medication that you legally cannot purchase without a doctor’s consultation.
If you require specific, daily medication, relocating to the city requires careful planning. You cannot simply mail a box of your prescriptions through international couriers; Customs and Excise will intercept the package, demanding import licenses and local medical justification, often resulting in the confiscation of the drugs. Reviewing the local Prescription Drug Laws: Bringing Foreign Medication into Hong Kong is non-negotiable before you pack your bags. You are generally permitted to carry a reasonable quantity for personal use in your checked luggage—usually a two to three-month supply—provided it is kept in the original packaging and accompanied by a clearly written, newly dated letter from your home country physician detailing your diagnosis and exact dosage.
Once your imported supply runs low, you must establish a pathway to refill it locally. For highly specialized drugs, your local GP may not have the authority or inventory to dispense them, forcing you to consult a private specialist just to get the required script. This can add thousands of dollars to the actual cost of the medication, reinforcing the need for comprehensive outpatient insurance coverage.
Accessing Chronic Illness Management
Managing a chronic condition like diabetes, hypertension, or a thyroid disorder requires a strategic blend of the public and private systems to avoid financial drain. Private specialists are excellent for the initial diagnosis, establishing the treatment protocol, and conducting annual deep-dive reviews of your condition. However, returning to a private clinic every single month just to pay a massive markup on your daily medication is financially unsustainable for most.
Savvy expats utilize a hybrid approach. They take their private specialist’s diagnostic reports to a public General Outpatient Clinic. While getting that first public appointment requires enduring the frustrating booking app, once you are registered in the HA system as a chronic care patient, the dynamic changes. You are placed on a structured, automated refill schedule.
You will periodically visit the public clinic for a rapid check-up, and they will dispense months’ worth of your required medication for a fraction of the private sector cost. The drugs dispensed by the Hospital Authority are generic, highly effective, and strictly regulated. By managing the routine drug supply through the public sector and saving the private sector for urgent interventions or second opinions, expats can effectively neutralize the ongoing financial burden of chronic illnesses.
Specialized Medical Services for the Expat Family
Pediatric Care and Childhood Immunizations
When relocating with children, establishing a trusted pediatric relationship is usually the highest priority. Unlike adults who can tough out a minor cold, children require immediate, specialized attention, often in the middle of the night. The private pediatric network in Hong Kong is superb, but it is heavily concentrated in upscale districts. Finding Expat-Friendly Pediatricians and Family Doctors often involves seeking out clinics with dedicated child waiting areas, isolation rooms for infectious diseases, and doctors who understand the specific anxieties of expat parents.
The administration of childhood vaccines presents a unique logistical puzzle. Hong Kong has a comprehensive, free Childhood Immunisation Programme administered through public Maternal and Child Health Centres (MCHCs). These centers are highly efficient, but they strictly adhere to the local Hong Kong vaccine schedule, which may not align perfectly with the schedule of your home country. For example, the timing of the MMR vaccine or the inclusion of certain meningitis strains might differ from what a British or American child requires for future school enrollment back home.
Many expat parents choose to navigate this by using the free public MCHCs for the bulk of standard vaccines, while utilizing private pediatricians to administer specific, supplementary vaccines required by their home countries. Private pediatricians can easily adapt to foreign schedules, procure the necessary global formulations, and provide detailed immunization records translated into English that seamlessly transfer to international school applications.
Dental Vision and Alternative Therapies
It is a jarring realization for many expats that the Hong Kong public healthcare system essentially provides zero routine dental care. Unless you require emergency maxillo-facial surgery following a severe trauma, you are entirely reliant on the private sector for your teeth. Dental clinics range from local neighborhood dentists practicing in small commercial spaces to sprawling, high-tech aesthetic dental centers in Central. The costs reflect this privatization. Researching Dental and Eye Care in Hong Kong: Costs, Clinics, and Coverage reveals that a simple check-up, scale, and polish can easily run between HKD 800 and HKD 1,500, while complex root canals or orthodontics reach tens of thousands of dollars.
Similarly, vision care is largely a private retail experience. Optometrists are highly regulated and operate out of optical shops located in nearly every mall. You can walk in, receive a comprehensive eye exam using state-of-the-art diagnostic equipment, and order prescription lenses on the same day. The eye exam itself is often free or nominally priced if you are purchasing frames from the retailer.
Beyond Western allopathic medicine, Traditional Chinese Medicine (TCM) is a heavily integrated, legally recognized component of the Hong Kong health landscape. Many expats who suffer from chronic pain, fatigue, or stress turn to registered TCM practitioners for acupuncture, cupping, and herbal therapies. Surprisingly, many premium health insurance policies now include specific sub-limits for registered TCM treatments, acknowledging its validity and widespread use in the local expat community for holistic health management.
Mental Health Support Systems
The most challenging aspect of healthcare in Hong Kong is navigating mental health support. The city is a high-pressure, hyper-competitive environment that frequently induces burnout, anxiety, and depression among the expat population. Unfortunately, mental health remains somewhat stigmatized in the broader local culture, which is reflected in the public healthcare system. The Hospital Authority’s psychiatric resources are severely overstretched. Unless a patient is deemed a direct, immediate threat to themselves or others, the wait time to see a public clinical psychologist or psychiatrist can exceed two years.
Consequently, expats must rely on the private sector for therapy and psychiatric medication management. The concentration of English-speaking psychologists is high, particularly in areas like Central and Stanley, but the financial barrier is immense. A standard 50-minute therapy session with a Western-trained clinical psychologist typically ranges from HKD 1,800 to HKD 3,000.
Because of these prohibitive costs, it is absolutely essential to scrutinize the fine print of any health insurance policy you purchase. Ensure that providers like Cigna Global have explicit, robust psychiatric and psychological counseling riders included in your plan. If local private care remains out of budget, a growing number of expats are turning to secure telemedicine platforms, utilizing their globally portable insurance to consult with therapists licensed in their home countries at a fraction of the Hong Kong private clinic rate.
Disclaimer
The information provided in this guide is for educational and informational purposes only and does not constitute professional medical or financial advice. Healthcare regulations, Hospital Authority policies, and private insurance frameworks in Hong Kong are subject to change. Always consult directly with a registered medical professional for health concerns and verify policy details with licensed insurance brokers to ensure coverage meets your specific needs.