Outpatient Department (OPD) vs Inpatient Billing Explained
Navigating the administrative labyrinth of Hong Kong’s medical system can feel like a full-time job when you are sick. I remember my first visit to a private clinic in Central; I was shocked that a ten-minute consultation cost more than my weekly groceries. This guide demystifies the complex billing differences between outpatient and inpatient care to save you from financial surprises.
Understanding Outpatient Care OPD in Hong Kong
Outpatient care, commonly referred to as OPD, encompasses any medical service where you are not formally admitted to a hospital overnight. In the context of Hong Kong, this is the most frequent interaction you will have with the healthcare system. It ranges from a quick visit to a local General Practitioner (GP) for a common cold to more specialized consultations for chronic conditions. The billing for these services is usually straightforward but can vary wildly depending on the district and the prestige of the clinic.
When you visit a private clinic, the bill is typically broken down into the consultation fee and the medication costs. It is a peculiar quirk of the Hong Kong system that many GPs dispense medication directly from their clinics. This means your final bill isn't just for the doctor’s time, but also for every pill and cream they prescribe. If you are Finding English-Speaking General Practitioners (GPs) in Central, expect to pay a premium. Consultation fees in these high-rent districts can start at HKD 800 and easily climb to HKD 2,000 before you’ve even stepped into the pharmacy section of the office.
Public outpatient services operate on a completely different financial model. If you hold a valid HKID, you are considered an Eligible Person (EP). At a public General Out-patient Clinic (GOPC), the fee is a flat, subsidized rate—currently around HKD 50 per visit, inclusive of basic medication. However, the trade-off is the waiting time. Booking a slot via the HA Go app can be a digital Hunger Games, as slots fill up within seconds of being released. For those who prefer a middle ground, many expats utilize Pharmacies and Medication in HK: Prescriptions and OTC Rules to manage minor ailments, but for anything requiring a diagnostic test like an X-ray or blood work, you are firmly in the OPD billing cycle.
Comprehensive plans from providers like Cigna Global often include a specific outpatient module. This is crucial because outpatient costs in Hong Kong are among the highest in the world. Without this coverage, routine check-ups, specialist referrals, and diagnostic imaging like MRIs (which can cost HKD 6,000 to HKD 12,000 in the private sector) will come directly out of your pocket.
Navigating Inpatient Billing and Hospitalization
Inpatient billing is triggered the moment you are "admitted" to a hospital bed. In Hong Kong, this usually involves an overnight stay, although some "Day Case" surgeries are also billed under inpatient rates for insurance purposes. The complexity of an inpatient bill in a private hospital like Matilda or Hong Kong Sanatorium can be overwhelming. Unlike the OPD bill, which is often a single page, an inpatient statement can be a multi-page document detailing everything from the "Room & Board" to the "Nursing Care" and even "Equipment Charges."
One of the most important things to understand about private inpatient care is the tiered pricing system. Hospitals categorize rooms into General Wards (3-6 beds), Semi-Private Rooms (2 beds), and Private Rooms. Your choice of room doesn't just dictate your comfort; it dictates the cost of every other service on the bill. If you choose a Private Room, the surgeon’s fee, the anesthetist’s fee, and the cost of laboratory tests will all be scaled up significantly. This "multiplier effect" is a common trap for new expats who assume their insurance covers everything. For those on a budget or with high-deductible plans like those offered by SafetyWing, opting for a General Ward is the most effective way to keep the total bill manageable.
Furthermore, private doctors in Hong Kong are often independent contractors. This means you will receive two separate sets of charges: the hospital charges (the facility, the room, the meds, the nurses) and the doctor’s fees (the surgeon, the anesthetist, and the "daily rounds" fee). It is not uncommon for a doctor to charge HKD 1,000 to HKD 3,000 just for the five-minute visit they make to your bedside each morning. When researching Private Hospitals in Hong Kong: Admission, Costs, and Insurance, always ask for a "medical quotation" before admission.
The public system, managed by the Hospital Authority, simplifies this immensely for residents. For an Eligible Person, the cost of a stay in an acute ward is roughly HKD 120 per day, with a one-time admission fee of HKD 75. This covers everything—surgery, medication, meals, and specialized care. However, if you do not have an HKID, you fall under the Hospital Authority Fees: Eligible Persons (EP) vs Non-Eligible Persons (NEP) category, where the daily rate can jump to over HKD 5,000, making private insurance or travel coverage essential.
Key Differences in Billing Structures
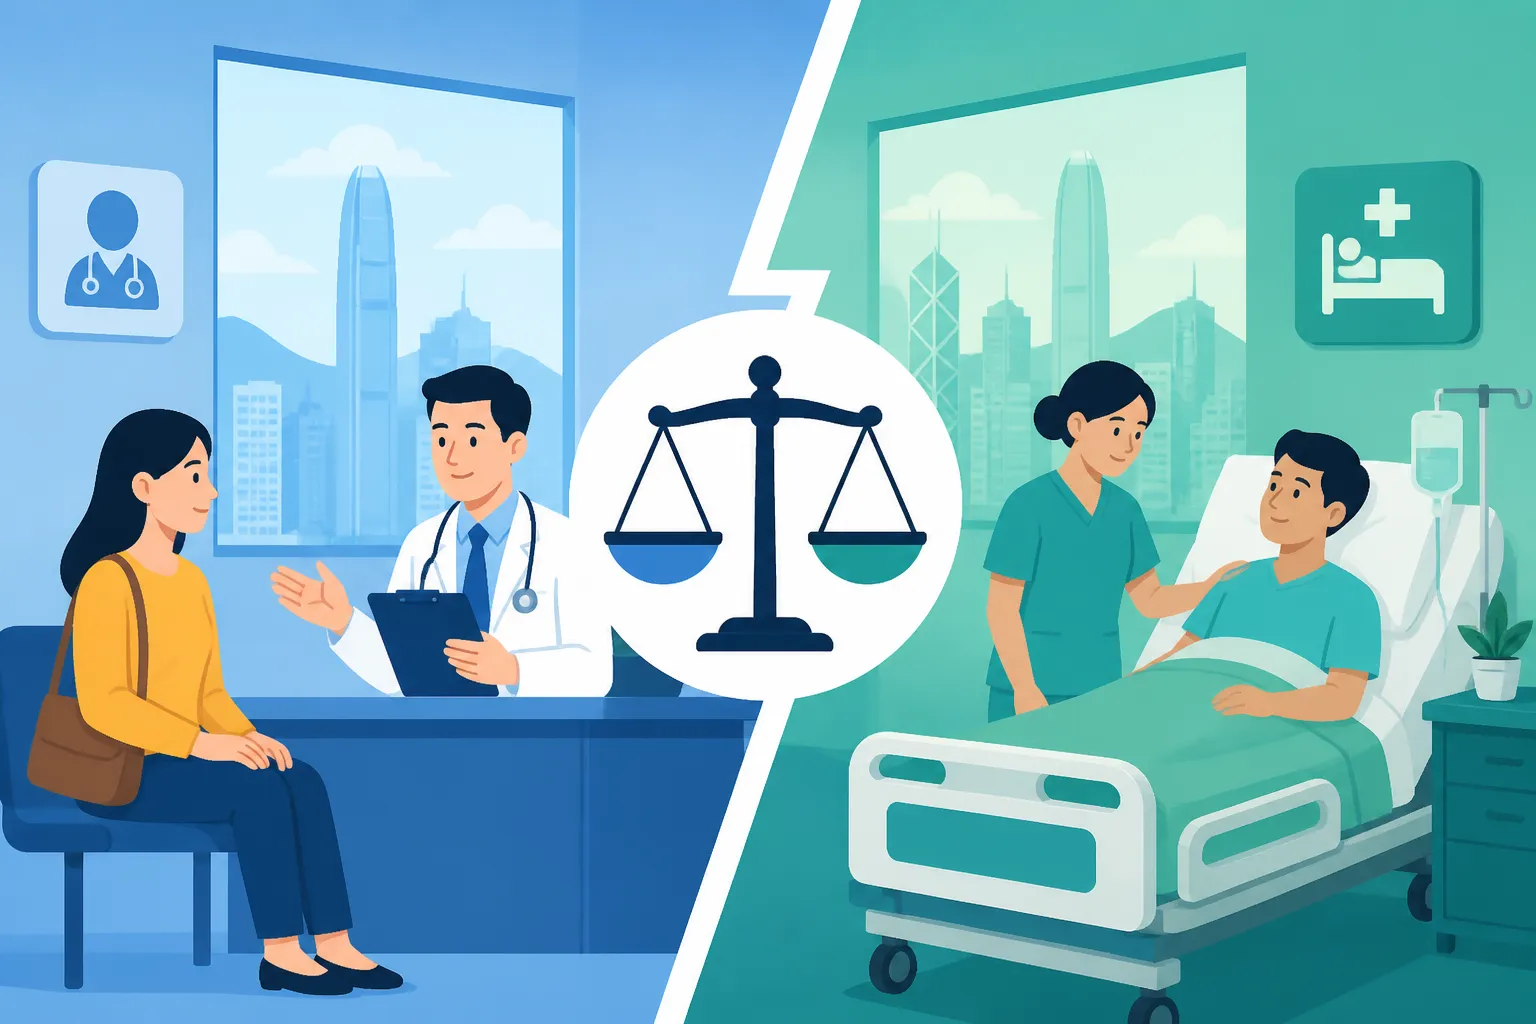
Understanding the fundamental split between OPD and inpatient billing is essential for managing your healthcare budget. OPD is generally "pay-and-claim" unless your clinic has a direct-billing arrangement with your insurer. Inpatient care, due to the high costs involved, almost always requires "Pre-Authorization" or a "Letter of Guarantee" (LOG) from your insurance company.
| Feature | Outpatient (OPD) | Inpatient (IPD) |
|---|---|---|
| Admission | None (Walk-in or Appointment) | Requires formal hospital admission |
| Billing Basis | Consultation + Medication + Tests | Room tier + Surgical fees + Professional fees |
| Payment Style | Often pay-and-claim | Direct billing (with Pre-Authorization) |
| Average Cost (Private) | HKD 1,000 – HKD 5,000 | HKD 50,000 – HKD 500,000+ |
| Public Rate (EP) | Flat fee (approx. HKD 50) | Daily rate (approx. HKD 120) |
| Insurance Focus | High frequency, lower cost | Low frequency, catastrophic cost |
A major pain point for many foreigners is the "Day Surgery" category. Imagine you need a gastroscopy. If you have it done in a specialist's clinic in Central, it is billed as OPD. If you have it done in a hospital as a day-patient, it might be billed as inpatient. Before you book, you must check your policy. Some plans only cover surgeries if they are performed in a hospital setting, while others prefer the lower cost of a clinic. If you are unsure, Finding a Direct-Billing Clinic for International Expat Insurance can save you the headache of paying a HKD 20,000 bill and waiting six weeks for reimbursement.
Another hidden aspect of inpatient billing is the "Miscellaneous" charge. This can include anything from the tissues in your room to the specific brand of bandage used after a blood draw. In the private sector, these costs are itemized and can add several hundred dollars to your final bill. Plans from Cigna Global are designed to handle these itemized complexities, whereas more nomadic or short-term plans like SafetyWing are excellent for emergency inpatient stays but might require more scrutiny regarding what "extras" they cover in a non-emergency scenario.
Strategic Management of Your Medical Expenses
Managing the financial side of your health in Hong Kong requires a proactive approach. You should never assume that your employer’s insurance is enough. Many group plans have "inner limits" for outpatient care—for example, they might only cover HKD 500 per GP visit, which won't even cover the consultation in a premium clinic. This is where VHIS vs Employer Group Medical Insurance: Do You Need Both? becomes a critical question for long-term residents.
To avoid billing surprises, always follow these three steps:
- The HKID Check: Ensure your HKID is always with you. Without it, you cannot access subsidized rates, and the billing clerk will automatically charge you as a non-resident, which can be a 50x price increase.
- Request a Detailed Estimate: For any specialist OPD procedure or any inpatient stay, the hospital is required to provide an estimate. Compare this against your insurance "Table of Benefits."
- Check the Direct Billing Network: Many private insurers have a list of "Network Doctors." If you stay within this network, the billing is handled between the doctor and the insurer. If you go "out of network," you will likely pay upfront and may only be reimbursed up to a certain "Reasonable and Customary" (R&C) limit.
If you are new to the city, reviewing an Essential Health Checklist for Your First 30 Days in Hong Kong will help you locate your nearest public A&E and a reliable private GP before an emergency strikes. If you ever feel you have been overcharged or treated unfairly in the billing process, you have the right to seek a review, which may involve Filing a Medical Complaint: The Medical Council of Hong Kong, though this is typically reserved for clinical negligence rather than purely financial disputes.
Expats often get burned by the "emergency room" trap. If you go to a private hospital's 24-hour outpatient clinic at 2:00 AM, you aren't just paying for the doctor; you are paying an "Emergency Call-out Fee" and "After-hours Surcharge." If it’s not a life-threatening situation, waiting until the clinic opens at 9:00 AM can save you thousands of dollars. Conversely, for a real emergency, the public A&E is the most cost-effective and often the best-equipped option, regardless of your insurance status.
Ultimately, the goal is to ensure that your focus remains on recovery, not on the rising total on a hospital monitor. By understanding that OPD is for the "routine and frequent" and inpatient is for the "serious and stay," you can align your insurance choices—whether through a premium provider like Cigna Global or a flexible option like SafetyWing—to match your lifestyle and risk tolerance in this high-cost medical hub.
Disclaimer
The information provided in this guide is for general informational purposes only and does not constitute professional medical or financial advice. Healthcare costs and policies in Hong Kong are subject to change, and you should always consult with your insurance provider or a qualified medical professional regarding your specific circumstances.